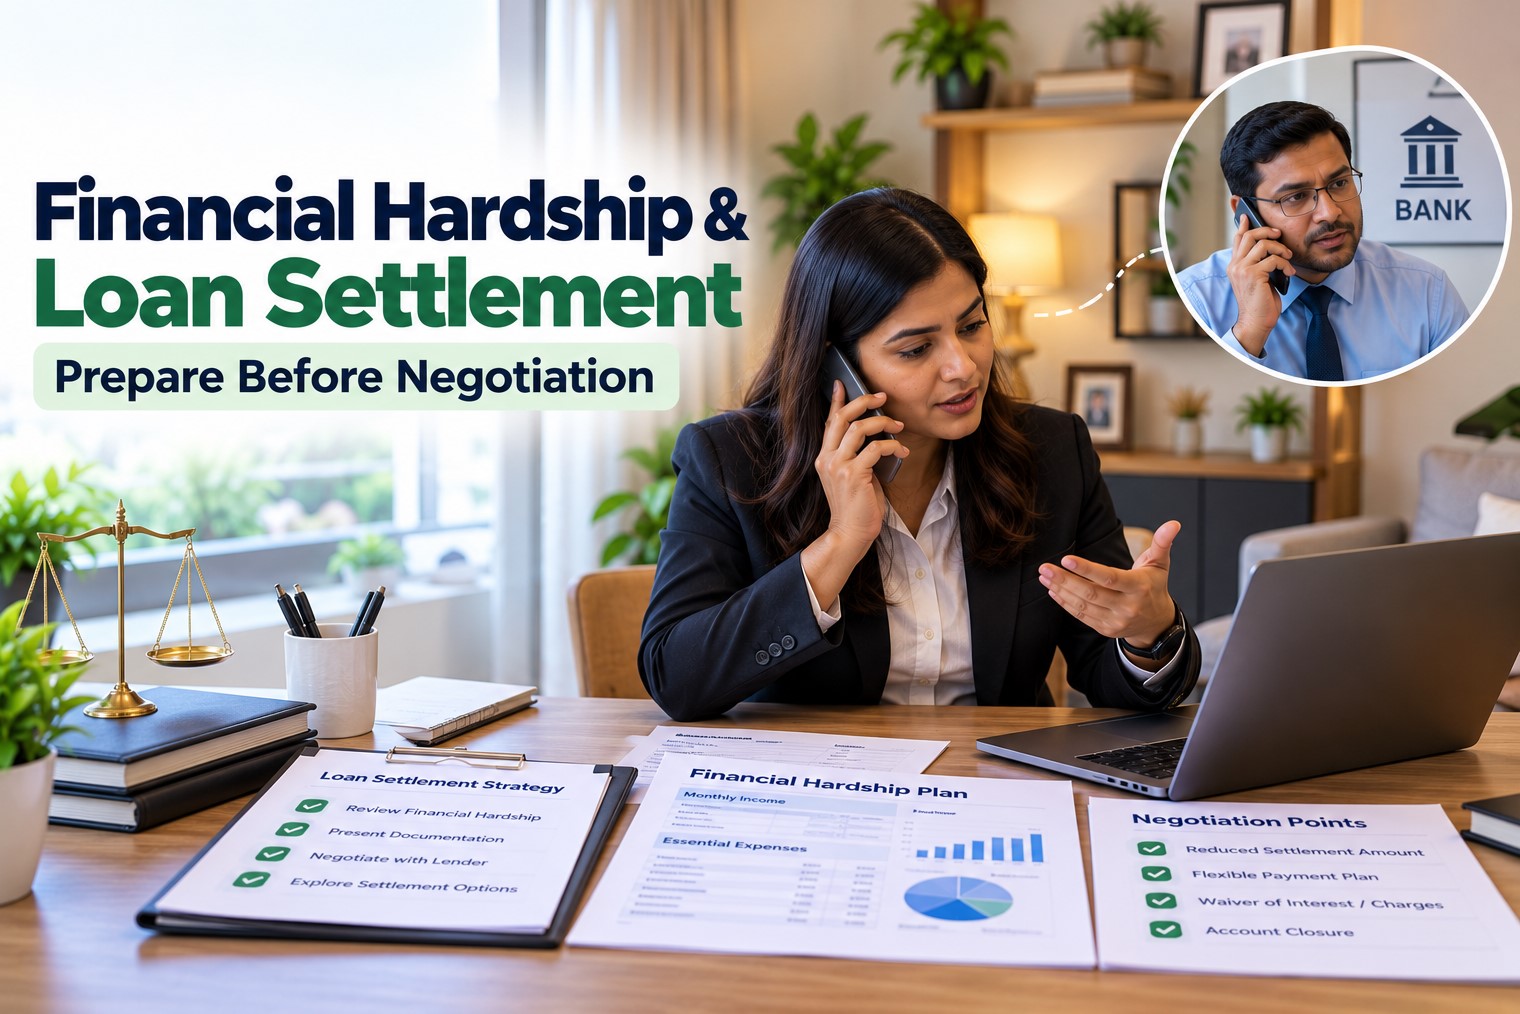
A financial hardship plan helps you explain why you are struggling to repay a loan, how much you can realistically afford and what repayment arrangement you want to discuss with your lender. Before requesting loan settlement, prepare a clear record of your income, essential expenses, outstanding debts and the financial event that caused your repayment difficulties.
A well-prepared plan does not guarantee that a bank or Non-Banking Financial Company (NBFC) will approve a settlement. However, it helps you present accurate information, understand your repayment capacity and compare available options. Depending on your circumstances, these may include regular repayment, restructuring or a negotiated settlement.
If you want to settle a loan because of job loss, reduced business income, medical expenses or another serious financial problem, avoid making a request based only on the amount you wish to pay. First, calculate what you can genuinely afford without neglecting essential household expenses or creating fresh debt.
This guide explains how Indian borrowers can prepare a financial hardship plan, collect supporting documents, write a request to their lender and approach loan settlement negotiations with realistic expectations.
What Is a Financial Hardship Plan for Loan Settlement?
A financial hardship plan is a written summary of your financial difficulties and your ability to repay outstanding debt. It explains what changed in your financial situation, how that change affected your EMIs and what arrangement you would like the lender to consider.
For example, a salaried borrower who loses a job may experience a sudden drop in income. A small business owner may face lower sales, delayed customer payments or higher operating costs. A family may face unexpected medical expenses that reduce the money available for loan repayments.
The plan should connect these circumstances to actual figures. Instead of simply saying that repayment has become difficult, explain your current income, essential expenses, outstanding loan balances and the amount you can realistically afford.
A financial hardship plan can support a request for:
- A revised repayment schedule, if the lender offers a suitable arrangement.
- Restructuring of the existing loan, subject to eligibility and lender policy.
- Temporary repayment relief, if available under the lender’s applicable policy.
- A negotiated settlement when full repayment is not realistically affordable and the lender is willing to consider it.
These options are not interchangeable. Your request should reflect your actual financial position rather than assume that settlement is the only possible solution.
When Should You Prepare a Financial Hardship Plan?
Prepare the plan as soon as you identify a genuine repayment problem. You do not necessarily need to wait until your account becomes overdue, although the available options may depend on your loan status and the lender’s policies.
Common situations include the following.
1. Job Loss or Reduced Salary
If you lose your job, face a salary reduction or experience a prolonged delay in receiving wages, your ability to pay EMIs may change immediately. Record the date the income reduction began, your previous income and your current reliable income.
If you have received severance pay or other temporary support, include it in your calculations without treating a one-time payment as permanent income.
2. Medical Expenses or Family Emergencies
Unexpected treatment costs, hospitalisation or continuing medical expenses can reduce your repayment capacity. Keep relevant bills and payment records, but submit only the personal information needed to support your request through a verified lender channel.
3. Business Losses or Irregular Income
Self-employed borrowers may experience lower sales, delayed invoices, seasonal income or increased operating expenses. Prepare a realistic picture of current cash flow rather than relying on an unusually profitable month or projected income that has not yet been received.
4. Multiple Loans and Growing Repayment Pressure
If you have personal loans, credit card dues and other EMIs, list every obligation. This helps you show why your available income cannot support all repayments.
If you are borrowing from one source to pay another, explain the pattern honestly. A fresh loan may not solve the underlying problem if your regular income remains insufficient.
Step 1: Calculate Your Actual Financial Position
Your negotiation should begin with numbers, not an estimated settlement percentage. Prepare a monthly budget that reflects your current circumstances.
Start by recording your reliable monthly income. Include salary, business income or other regular sources after accounting for necessary business costs and deductions. Do not count uncertain future earnings as guaranteed income.
Next, list essential expenses such as:
- Rent or basic housing costs.
- Food and household supplies.
- Electricity, water, telephone and essential transport.
- Medical expenses and necessary insurance payments.
- School fees and dependent care.
- Essential business costs, if you are self-employed.
Then record your existing debt obligations, including loan EMIs, credit card dues, overdue amounts and other contractual repayments.
For example, suppose a borrower in Jaipur earns ₹35,000 per month after deductions. Essential household expenses are ₹21,000, and other unavoidable expenses average ₹3,000. The amount remaining before debt repayments is ₹11,000.
This does not mean the borrower can automatically offer ₹11,000 towards a settlement. The borrower may need a reasonable emergency buffer, and other debts may also require attention. The example simply shows why an offer should be based on a complete budget rather than a guessed figure.
If the calculations show that even normal repayments are unaffordable, discuss the situation with your lender and explore available alternatives before committing to an amount you may not be able to pay.
Step 2: Identify the Cause and Duration of Your Hardship
A lender may need to understand not only how much you can pay but also why your financial position has changed.
Prepare a short timeline covering:
- When the financial problem began.
- What caused the reduction in your repayment capacity.
- How your income or essential expenses changed.
- Whether the problem is temporary or likely to continue.
- What steps you have taken to manage your finances.
For example, a borrower whose salary was reduced for three months may have a different repayment outlook from someone who has lost employment and has no confirmed new job.
Avoid exaggerating the situation or making claims you cannot support. If your income is uncertain, state that clearly. Accurate information is more useful than a promise that your finances will improve by a particular date without reasonable evidence.
Step 3: Collect Documents to Support Your Request
The documents you need will depend on the lender, the type of loan and the reason for hardship. Prepare relevant records before contacting the lender so you can explain your circumstances consistently.
| Document | Why it may help |
|---|---|
| Recent salary slips or income records | Shows your current earnings and any reduction in income |
| Bank statements | Helps establish actual cash flow and regular expenses |
| Termination letter or salary-reduction communication | Supports a job-loss or employment-related hardship claim |
| Medical bills and treatment records | Documents significant health-related expenses |
| Business income and expense records | Helps self-employed borrowers explain reduced cash flow |
| Loan statements and repayment schedules | Shows outstanding balances, EMIs and overdue amounts |
| Credit card statements | Helps establish other repayment obligations |
| Monthly budget | Summarises income, essential costs and realistic repayment capacity |
| Existing lender correspondence | Provides a record of previous requests, offers or discussions |
Do not send every personal document to an unknown intermediary. Verify the recipient and use an authorised bank or NBFC communication channel. Keep copies of all documents you submit.
Step 4: Decide What You Want to Request
Before approaching the lender, decide which outcome best fits your financial situation.
If you can repay the full amount but need a manageable schedule, ask whether restructuring or another repayment arrangement is available. A longer tenure may reduce monthly instalments but can increase total interest costs.
If your financial position has recovered and you can meet the existing schedule, continuing regular repayment may be the simplest option.
If you cannot realistically repay the full debt despite reviewing your budget, you may ask whether the lender will consider a negotiated settlement. Your request should explain your hardship and proposed payment capacity, but you should not assume the lender will accept a particular amount.
For borrowers exploring Personal Loan Settlement, the relevant factors may include the account’s repayment history, outstanding balance, documented hardship and the lender’s settlement policy. The process may differ for credit cards, secured loans and other facilities.
If you have multiple debts, also consider whether a broader Debt Settlement or repayment strategy is needed. A plan that resolves one account but leaves every other repayment unaffordable may not solve your overall financial problem.
Step 5: Write a Clear Financial Hardship Request
A hardship request should be concise, factual and supported by relevant records. It does not need emotional language or lengthy personal details.
Include these elements:
- Your name and relevant loan account reference.
- A brief explanation of the financial difficulty.
- The date the problem began and its effect on your income.
- Your current income and essential expenses.
- A summary of your existing repayment obligations.
- The repayment arrangement you want the lender to consider.
- A list of supporting documents.
- A request for written communication about the available options.
Sample Financial Hardship Letter to a Bank or NBFC
Subject: Request for Review of Loan Repayment Options Due to Financial Hardship
Dear Sir/Madam,
I am writing to request a review of the repayment options available for my loan account due to a change in my financial circumstances.
My repayment capacity has been affected by [briefly explain the reason, such as job loss, reduced income, medical expenses or business losses]. This situation began in [month/year] and has affected my ability to meet the existing repayment schedule.
My current monthly income is approximately ₹[amount], while my essential monthly expenses are approximately ₹[amount]. I have reviewed my financial position and am willing to discuss a repayment arrangement that reflects my actual capacity.
I request you to review my account and inform me whether restructuring, a revised repayment schedule or a negotiated settlement may be considered under your applicable policy.
I can provide relevant income records, bank statements, expense details and supporting documents for your assessment. Please share the available options and applicable terms in writing.
Thank you for your consideration.
Yours faithfully,
[Full Name]
[Loan Account Reference]
[Registered Contact Details]
Use only the parts that apply to your situation. Requesting settlement does not mean you have to stop communicating with the lender or ignore existing contractual obligations while awaiting a response.
Step 6: Prepare for the Negotiation
Once your documents are ready, approach the lender through its authorised customer service, loan servicing, grievance or settlement channel, as applicable.
During the discussion, be prepared to explain:
- Why you cannot maintain the current repayment schedule.
- How much you can afford and when the funds will be available.
- Whether the proposed payment is a one-time amount or depends on future income.
- Whether other loans or essential expenses limit your capacity.
- What repayment alternatives you have already considered.
Do not promise money that you expect to borrow at a high cost simply to secure an agreement. If your proposed payment depends on selling an asset, receiving family assistance or collecting a business payment, explain any uncertainty.
You should also ask the lender to clarify the amount due, applicable charges, payment deadline and whether the proposal resolves the full claim under the agreed terms. If the lender offers settlement, review the written offer carefully before paying.
A borrower seeking One Time Settlement should pay particular attention to the settlement amount, validity period, payment instructions, consequences of missing the deadline and the account status that will be reported after completion.
RBI Guidelines and Important Legal Considerations
The Reserve Bank of India issued its Framework for Compromise Settlements and Technical Write-offs on 8 June 2023. The framework requires covered regulated entities to maintain board-approved policies governing compromise settlements and technical write-offs. It does not create an automatic right for every borrower to settle a loan for a reduced amount.
A lender assesses settlement requests under its applicable policy and the circumstances of the account. Your financial hardship plan can help explain your position, but it cannot compel the lender to approve a proposal.
Keep these distinctions in mind:
- Restructuring changes the terms of repayment under an agreed arrangement. It does not automatically cancel the debt.
- Compromise settlement involves a negotiated arrangement to resolve the lender’s claim according to the agreed terms.
- Technical write-off is an accounting treatment. It does not, by itself, waive the lender’s claim against the borrower.
If legal proceedings are already underway, a settlement may require additional formalities. Do not ignore court notices, arbitration communications or other formal documents. Seek qualified legal advice where necessary.
For concerns about lender conduct, use the lender’s grievance redressal process first and review the relevant RBI complaint mechanism where applicable. A grievance process is not a substitute for negotiating the financial terms of a loan, and it does not guarantee settlement approval.
How Settlement Can Affect Your Credit Report
If a lender accepts less than the full amount originally due, the account may be reported as settled rather than closed after full repayment. The precise reporting depends on the account, the settlement terms and applicable reporting requirements.
Credit Information Companies maintain credit information supplied by lenders. An account’s reported status can influence how future lenders assess an application, although the effect on a particular credit score or future approval cannot be predicted with certainty.
Before accepting an offer, ask the lender how the account will be reported after you fulfil the settlement terms. Keep the settlement letter, payment receipts and completion confirmation. Later, review your credit report and raise a dispute if the reported information is inaccurate.
You can also learn more about Credit Score After Loan Settlement before deciding whether settlement is suitable for your longer-term financial plans.
Mistakes to Avoid During Financial Hardship Negotiation
A hardship plan is useful only when it reflects your actual finances and supports an informed decision. Avoid these mistakes:
- Offering an unrealistic amount: A high offer may be difficult to honour if your budget does not support it.
- Hiding other debts: Incomplete information can lead to an unsuitable repayment proposal.
- Relying on verbal assurances: Ask for formal terms through an authorised lender channel.
- Paying an unverified intermediary: Confirm who is authorised to communicate or collect payment on behalf of the lender.
- Assuming settlement is guaranteed: The lender may reject the proposal or offer another arrangement.
- Ignoring credit consequences: Understand how the account may be reported after settlement.
- Using new high-cost borrowing to fund settlement: This may replace one unaffordable obligation with another.
- Failing to retain records: Keep copies of submissions, correspondence, payment proof and the final agreement.
If a settlement proposal is rejected, ask whether the lender can explain the available repayment options. Reassess your budget and submit further information only if it accurately reflects a change or clarification in your circumstances.
Frequently Asked Questions
1. What is a financial hardship plan for loan settlement?
It is a written summary of your income, expenses, debts and the financial problem affecting your repayments. It helps you explain your circumstances and request a suitable arrangement from your lender.
2. Can I request loan settlement before my EMI becomes overdue?
You can contact your lender before a missed payment and explain your financial difficulty. Whether settlement is available at that stage depends on the lender’s policy and your circumstances. Do not assume that an early request guarantees approval.
3. Does a financial hardship letter guarantee loan settlement?
No. The letter explains your circumstances and supports your request, but the lender decides whether to offer settlement under its applicable policy. It may instead discuss restructuring or another repayment arrangement.
4. What amount should I offer during loan settlement negotiation?
Base any proposed amount on your actual financial capacity and the funds you can reasonably access. There is no universal settlement percentage that applies to every lender or borrower. Obtain written confirmation of any accepted offer before making payment.
5. Can self-employed borrowers prepare a financial hardship plan?
Yes. Self-employed borrowers can document changes in revenue, operating expenses, customer payments and available cash flow. Bank statements and business records may help demonstrate why the existing repayment schedule has become difficult to maintain.
6. Should I stop paying EMIs while the lender reviews my request?
Do not assume that submitting a request suspends your contractual obligations. Unless the lender formally agrees to a change, missed payments may lead to charges, collection activity and adverse credit reporting. Ask the lender to confirm your current obligations in writing.
7. Can I negotiate settlement for more than one loan?
You can approach each relevant lender to discuss your circumstances, but each account may be assessed separately. Prepare an overall debt plan so that a proposal for one loan does not leave you unable to manage your other obligations.
8. What if the lender rejects my hardship request?
Ask about the alternatives available under its policy, such as a revised repayment schedule or restructuring, if eligible. Review your budget again and provide additional supporting information if your circumstances warrant it. If the dispute concerns an error or lender conduct, consider the relevant grievance process.
9. Will the lender remove my negative credit history after settlement?
Settlement does not automatically erase accurate historical information. The lender may report the account as settled, and future lenders may consider that status. Check the written terms and review your credit report after completion.
10. How long does a loan settlement negotiation take?
There is no universal timeline. It depends on the lender’s process, the completeness of your documents, the account’s status and the approvals required. Ask the lender for an expected response timeline and keep a record of follow-ups.
Prepare Before You Make Your Request
A financial hardship plan gives you a practical starting point when loan repayments no longer fit your circumstances. By calculating your available income, documenting the cause of hardship and organising supporting records, you can explain your position clearly and compare the options available from your lender.
Settlement may be worth discussing when full repayment is genuinely unaffordable, but it should not be treated as an automatic entitlement or a guaranteed outcome. Review restructuring and repayment alternatives as well, understand the credit-reporting consequences and obtain every accepted term in writing.
A well-supported request cannot guarantee approval, but it can help you make a more informed proposal and avoid commitments that your finances cannot sustain.