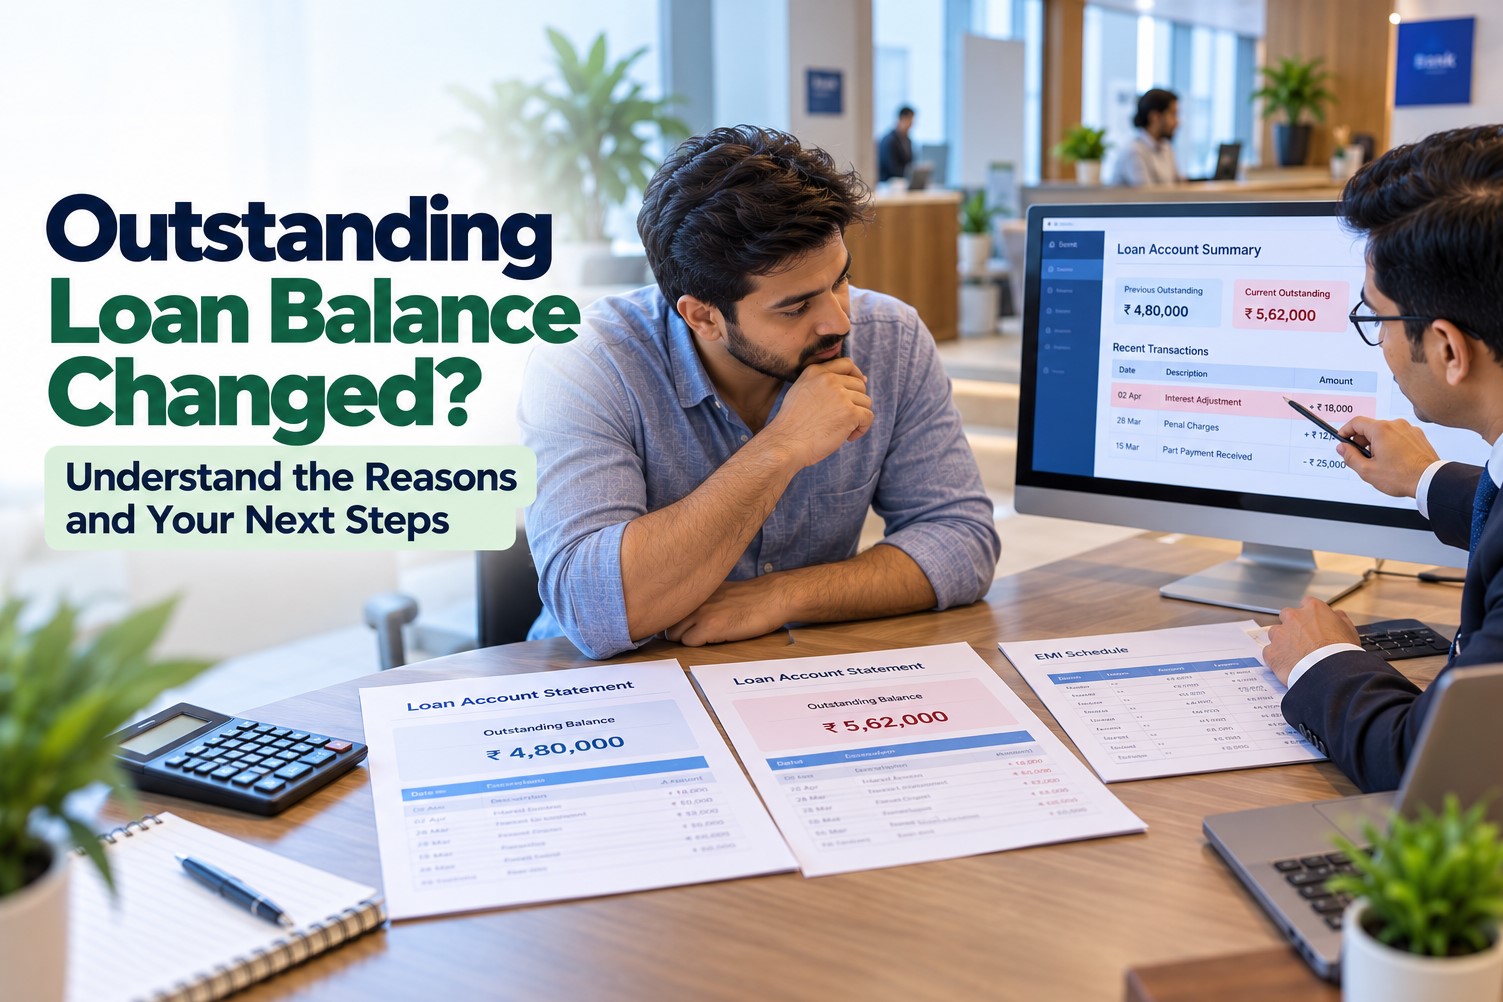
If your bank has changed the outstanding balance on your loan account, the reason may be a recent EMI payment, interest calculation, overdue charges, a payment reversal, an account correction, or a change approved under a repayment arrangement. In some cases, the balance may increase even when you have been making payments regularly. In others, it may decrease because the bank has credited a payment or corrected an earlier entry.
A change in your outstanding loan balance does not automatically mean that the bank has made a mistake or waived part of your debt. You need to compare the latest loan statement with your previous statement and identify the transactions responsible for the difference.
Start by checking the principal outstanding, interest charged, payments received, overdue amounts, fees, and any reversals or adjustments. If the bank has changed your balance under a restructuring or loan settlement arrangement, review the written terms before assuming the account has been updated correctly.
If the revised amount does not match your records, request a detailed explanation from the bank or Non-Banking Financial Company (NBFC). Keep your payment receipts, account statements, and written communications. If the issue remains unresolved, use the lender’s grievance process and consider the applicable RBI complaint mechanism.
What Does an Outstanding Loan Balance Mean?
Your outstanding loan balance is the amount that remains payable on your loan account at a particular time. However, the exact figure displayed in a banking app may not always be the same as the amount required to close the loan immediately.
Depending on the lender and the loan product, the displayed balance may reflect the principal outstanding, while the total amount payable may also include accrued interest, overdue instalments, applicable charges, or other contractual dues.
For example, a borrower may see a principal outstanding of ₹2,40,000 in the loan account. If an EMI is overdue and interest or permitted charges have accrued, the total amount required to regularise or close the account could be different.
Before taking action, establish which amount you are viewing:
- Principal outstanding: The unpaid principal amount of the loan.
- Total outstanding dues: The amount currently due under the loan account, which may include interest, overdue instalments, and applicable charges.
- Foreclosure or closure amount: The amount quoted by the lender to close the loan on a specified date, subject to the applicable terms.
- Settlement amount: The amount agreed with the lender under an approved settlement arrangement, if one exists.
These figures serve different purposes. Comparing them without understanding the difference can lead to confusion.
Why Has the Bank Changed Your Outstanding Loan Balance?
A bank can update a loan account when it records a payment, applies interest, posts a permitted charge, reverses an entry, or corrects an earlier transaction. The reason should be identifiable from the account statement or the lender’s explanation.
1. Your EMI payment has been credited
When your EMI is credited, the lender generally allocates the payment according to the loan agreement and applicable repayment rules. Part of the EMI may go towards interest, while the remaining amount reduces the principal.
This means your outstanding principal may decrease by less than the total EMI paid.
For example, if your EMI is ₹15,000, the entire ₹15,000 may not reduce your principal. The allocation between principal and interest depends on your repayment schedule and account status.
If you have paid an EMI but the balance has not changed as expected, check whether the payment has been credited to the correct loan account and whether the statement includes the latest transaction.
2. Interest has been added to the account
Interest can cause the amount shown as outstanding to increase. This may happen when interest accrues between statement dates, an EMI remains unpaid, or the account is overdue.
The impact depends on the loan agreement, interest rate, repayment schedule, and applicable rules. A change in the interest rate may also affect future interest calculations for certain floating-rate loans.
Suppose your previous statement showed ₹1,80,000 outstanding. A later statement may show a higher amount if interest has accrued and no corresponding payment has reduced the dues.
Ask the lender to explain the applicable interest rate, the period for which interest was charged, and the calculation used.
3. Overdue charges or other fees have been applied
An overdue EMI can lead to additional amounts becoming payable under the loan agreement and applicable rules. Depending on the facility, these may include applicable penal charges or other permitted fees.
Do not assume every new charge is correct simply because it appears in the statement. Check the description, amount, date, and contractual basis of the charge.
If a fee appears to be duplicated, was charged after payment, or does not match the lender’s explanation, request a transaction-level clarification.
4. A payment has been reversed
Sometimes a payment initially appears in the account but is later reversed. This can happen when a transaction fails, is returned, or is reversed during processing.
For example, your banking app may initially show an EMI payment of ₹12,000. If the transaction subsequently fails or is reversed, the lender may restore the amount previously due. Your outstanding balance can therefore increase again.
Check both your bank account and loan statement. A debit from your bank account does not always establish that the lender has permanently credited the payment.
If money was debited but the EMI remains unpaid, provide the transaction reference number and payment proof to both relevant institutions, where necessary.
5. The bank has corrected an earlier entry
Lenders may correct an account entry when they identify a posting error, a duplicate transaction, or a mismatch in the recorded payment or charge.
A correction can increase or decrease the displayed balance. The direction of the change alone does not establish whether it is correct.
Ask for the original entry, the corrected entry, the date of correction, and the reason. Compare the adjustment with your payment records and previous statements.
6. Your loan terms have changed
An approved restructuring arrangement or another documented change to the loan terms can affect the repayment schedule, instalment amount, interest treatment, or other account details.
However, a change to the repayment schedule does not automatically mean the principal has been reduced. Obtain the revised repayment schedule and compare it with the previous one.
If you agreed to a new arrangement but the account still reflects the old EMI or an unexpected amount, ask the lender when the revised terms took effect and whether any earlier dues remain payable.
7. The account has been settled or adjusted
If your lender has approved a loan settlement, the amount payable may change according to the written settlement agreement. The account should be handled according to the agreed amount, payment conditions, and applicable reporting procedures.
A settlement discussion or verbal assurance is not the same as an approved settlement. Until the lender confirms the arrangement, do not assume the remaining dues have been waived.
Similarly, an accounting write-off by a lender does not, by itself, mean that the borrower no longer owes the debt. Ask for written confirmation of the account’s status and any remaining obligations.
How to Check Whether the Revised Loan Balance Is Correct
Do not rely only on the amount displayed on the home screen of a banking app. Review the detailed account statement and identify the transactions that explain the change.
Follow this process.
Step 1: Download two loan statements. Obtain the statement before the balance changed and the latest available statement. Make sure the dates overlap sufficiently to show the relevant transactions.
Step 2: Identify the opening and closing balances. Check the balance at the beginning and end of the period. Note the dates on which the lender recorded the change.
Step 3: Review every transaction. Look for EMI credits, interest entries, fees, reversals, refunds, adjustments, and other debits or credits.
Step 4: Match payments with your bank records. Compare the EMI dates and amounts against your bank statement, payment receipt, UPI reference, or transaction confirmation.
Step 5: Check the repayment schedule. Review the EMI amount, interest rate, remaining tenure, and allocation of principal and interest. If the terms have changed, obtain the revised schedule.
Step 6: Ask for a written reconciliation. If the difference remains unclear, request the lender to explain how the previous balance became the revised balance.
For borrowers managing several accounts, maintaining a simple repayment record can help identify discrepancies early. You can also review the loan repayment schedule alongside your bank statement to understand how the principal should change over time.
Practical Example: Understanding a Balance Change
Consider an Indian borrower with a personal loan who checks the loan account after paying an EMI.
The previous statement showed a principal outstanding of ₹2,50,000. The borrower expected it to decrease after making the payment, but the latest statement shows a smaller reduction than expected.
The borrower should not immediately conclude that the bank has made an error. The EMI may have covered interest accrued during the period, with only the remaining amount reducing the principal. There may also be an overdue amount, a payment reversal, or a transaction that has not yet been posted.
The correct approach is to compare the EMI credit, interest entry, and closing principal with the repayment schedule. If the figures still do not reconcile, the borrower should ask the lender for a detailed calculation.
This example illustrates why a changed balance must be investigated using transaction records rather than assumptions.
What If the Bank Has Reduced Your Outstanding Loan Balance?
A lower balance may indicate that a payment has been credited, an earlier charge has been reversed, an excess amount has been adjusted, or a revised arrangement has been processed.
It may also reflect a correction or another account adjustment. Therefore, a lower balance should not automatically be treated as confirmation that the loan is closed or that the remaining amount has been waived.
If the reduction follows a settlement agreement, check whether the lender has confirmed that all required settlement payments have been received and the agreed conditions have been fulfilled.
If the reduction appears without an explanation, request written confirmation of:
- The reason for the adjustment.
- The amount credited or waived, if applicable.
- The remaining principal and total dues.
- Any further payment required.
- The account status after the adjustment.
Retain the confirmation with your loan records. If you intend to close the account, request the lender’s official closure requirements rather than relying on a balance displayed in the app.
How Loan Settlement Can Affect the Outstanding Balance
Loan settlement is relevant when a borrower is experiencing serious financial difficulty and cannot reasonably repay the full contractual dues. Under an approved settlement, the lender agrees to accept a specified amount under documented conditions.
For example, a borrower with outstanding dues of ₹2,00,000 may receive a written offer to settle the account for a lower amount. The actual amount depends on the lender’s decision and the circumstances; there is no universal settlement percentage applicable to every borrower.
Before paying, check the settlement letter for the account details, agreed amount, due dates, payment conditions, and treatment of the remaining dues after successful completion.
Also understand the possible credit-reporting consequences. A lender may report an account as “settled” rather than “closed” when less than the full contractual dues have been accepted. This may affect how future lenders assess a credit application.
If you need to understand the process, review the requirements for one-time loan settlement and confirm all terms directly with your bank or NBFC.
RBI Guidelines and Your Right to Raise a Dispute
Banks and NBFCs in India must follow applicable laws, regulatory requirements, and their contractual obligations when maintaining loan accounts. The Reserve Bank of India (RBI) has issued directions covering various aspects of lending, customer service, grievance handling, and resolution of stressed accounts.
However, an unexpected change in a loan balance does not automatically prove a regulatory violation. The underlying transaction and the applicable loan terms must be examined first.
If you believe the amount is incorrect, take these steps:
- Submit a complaint through the lender’s official customer-service or grievance-redressal channel.
- Include your loan account reference, the dates and amounts in dispute, and supporting payment records.
- Request a written transaction-wise reconciliation and correction if an error is established.
- Retain the complaint reference number and the lender’s response.
- If the complaint is rejected or remains unresolved, check whether you can approach the RBI Integrated Ombudsman Scheme. Eligibility depends on the nature of the complaint and compliance with the scheme’s conditions, including the applicable process and timelines.
Do not ignore a repayment demand or legal notice while a dispute is being investigated. If the issue involves a secured asset, guarantor, court proceedings, or a substantial disputed amount, consider obtaining qualified legal advice.
Documents to Keep When Disputing a Loan Balance
Good records help the lender identify and investigate the issue. Keep copies of the documents relevant to your case:
- Previous and current loan account statements.
- EMI payment receipts and bank statements.
- UPI, NEFT, IMPS, or other transaction references.
- The original loan agreement and repayment schedule.
- Revised terms, restructuring documents, or settlement letters.
- Details of charges or adjustments you dispute.
- Emails, complaint numbers, and written responses from the lender.
Share documents only through verified channels. Avoid sending full banking credentials, passwords, PINs, or OTPs to anyone claiming to resolve the issue.
Common Mistakes to Avoid
Assuming a lower balance means the loan is closed: The account may still have unpaid interest, charges, or other dues. Obtain a written closure confirmation.
Ignoring a higher balance: Interest, a reversed payment, or an overdue charge may explain the change, but you should verify it instead of assuming it is correct.
Relying only on a phone conversation: Keep a written record of the complaint, the lender’s explanation, and any agreed correction.
Paying a third party to correct the account: Verify the process directly with the lender and make payments only through authorised channels.
Confusing a write-off with a waiver: A lender’s accounting treatment does not automatically cancel the borrower’s repayment obligation.
Assuming settlement removes all credit-history consequences: Confirm the final account status and check the information reported to Credit Information Companies.
Frequently Asked Questions
1. Can a bank increase my outstanding loan balance after I have paid an EMI?
Yes, the displayed balance can increase if interest or permitted charges are added, a payment is reversed, or an earlier entry is corrected. Check the statement and ask the lender to explain the specific transaction.
2. Why has my loan balance not decreased by the full EMI amount?
An EMI generally covers both interest and principal. Only the portion allocated to principal reduces the principal outstanding. Check the repayment schedule to understand the allocation.
3. What should I do if my bank shows an incorrect loan amount?
Download your statement, collect payment proof, identify the disputed entry, and submit a written complaint through the lender’s official grievance channel. Request a transaction-wise reconciliation and retain the complaint reference.
4. Can a bank change my loan balance without informing me?
Account balances can change as transactions and contractual charges are posted, but the lender should be able to explain the entries and applicable terms. If an adjustment is unexplained, request written clarification and check the loan agreement and relevant customer-service requirements.
5. Does a lower outstanding balance mean my loan has been settled?
No. A lower balance may result from an ordinary payment or adjustment. A settlement requires an approved arrangement and fulfilment of its conditions. Obtain written confirmation of the final account status.
6. Can a bank add interest after my loan becomes overdue?
Interest and other amounts may continue to accrue according to the loan agreement and applicable rules. Ask for the calculation, period, rate, and basis of every disputed charge.
7. Will a loan balance correction improve my CIBIL score?
Not necessarily. A corrected balance may help ensure that accurate account information is maintained, but the effect on your credit profile depends on what was incorrect and how the lender reports the account. Check your credit report after the correction is processed.
8. Does a loan write-off mean I no longer have to repay the bank?
No. A write-off is generally an accounting action and does not by itself waive the debt. Ask the lender to confirm the amount outstanding and whether any settlement, waiver, or closure has been formally approved.
9. Can I complain to the RBI about an incorrect loan balance?
You can check whether your complaint qualifies under the RBI Integrated Ombudsman Scheme after following the applicable process with the lender. Eligibility depends on the type of complaint, the lender, and the scheme’s conditions.
10. What if my loan balance changes after a settlement payment?
Compare the account statement with the written settlement terms and payment receipt. If the expected adjustment has not been made, contact the lender with the settlement letter and transaction proof. Request confirmation of the remaining dues and account status.
Conclusion
A change in your outstanding loan balance can result from a payment, interest, an overdue charge, a reversed transaction, an account correction, or an approved change to your repayment terms. The important step is to identify the exact transaction behind the difference before deciding whether the amount is correct.
Compare your statements, match payments with bank records, and ask the lender for a written explanation whenever the figures do not reconcile. If an error is confirmed, request correction and check the updated account statement and credit report where relevant.
For borrowers facing genuine repayment difficulty, understanding the outstanding amount is also an important first step before considering restructuring or settlement. Settle Loan can help you understand the loan settlement process and prepare questions for discussion with your lender. Any settlement, waiver, or account correction remains subject to the lender’s approval, the written terms, and applicable law.