If your outstanding loan balance keeps increasing even though you pay your EMIs regularly, do not assume that the lender has made a mistake or that your payments have been wasted. The reason may be the way interest is calculated, a change in the interest rate, overdue charges, unpaid amounts from earlier months or an error in your loan statement.
Start by comparing your latest loan statement with the repayment schedule and checking how each EMI has been adjusted between principal, interest and other charges. Ask your lender for a detailed explanation if the numbers do not match. If the balance is correct but your income can no longer support the repayment plan, explore restructuring or other repayment arrangements before the situation worsens.
Loan settlement may be an option when genuine financial hardship makes repayment unsustainable, but it is not the first solution for every growing loan balance. A settlement can affect your credit history and is subject to the lender’s approval. Understanding the reason behind the increasing balance will help you choose the right next step.
Why Does Your Outstanding Loan Balance Keep Increasing?
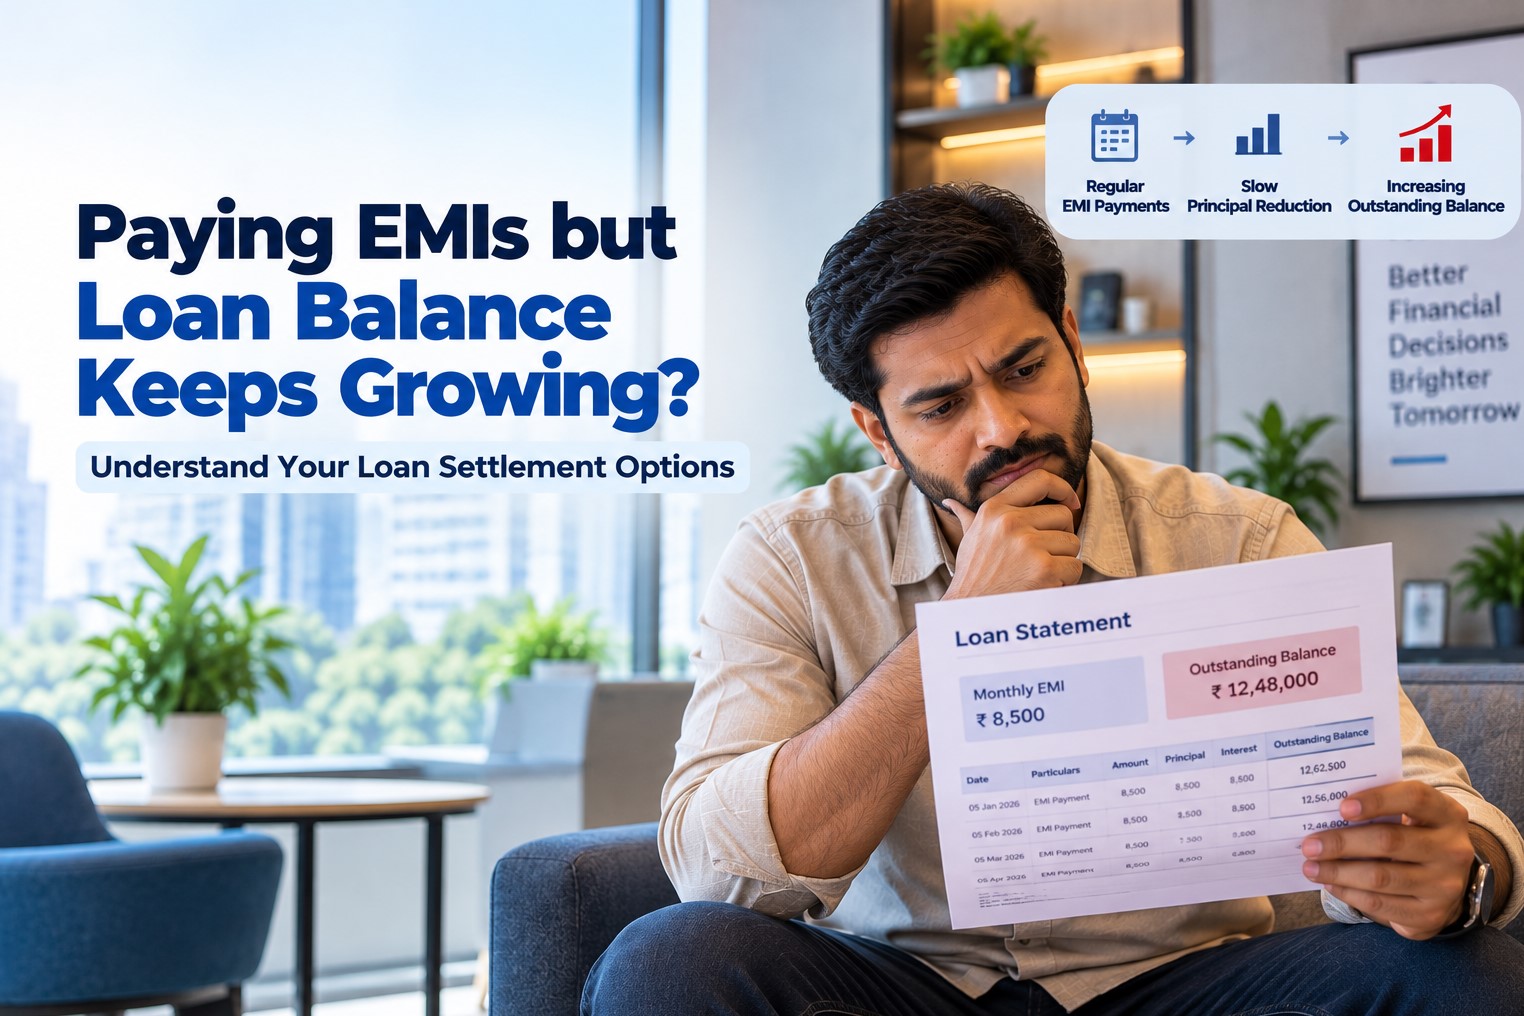
A loan balance does not always fall by the same amount after every EMI. The principal portion of an instalment depends on the loan terms, applicable interest rate, repayment schedule and any unpaid amounts or charges.
The following are common reasons for a balance that appears to be stuck or keeps growing.
1. A Large Part of Your EMI Goes Towards Interest
An EMI generally covers both principal and interest. At the beginning of many amortising loans, a larger share of the EMI goes towards interest. The remaining amount reduces the principal.
For example, suppose your monthly EMI is ₹12,000. If ₹8,000 goes towards interest and ₹4,000 towards principal, your principal falls by only ₹4,000 that month, assuming there are no other adjustments.
This does not automatically indicate a problem. However, if the principal reduction is much lower than expected, check the applicable interest rate, outstanding principal and repayment schedule.
2. Your Floating Interest Rate Has Increased
Some loans have floating interest rates linked to an external benchmark or another reference rate specified in the loan agreement. When the applicable rate changes, the lender may revise the EMI, the loan tenure or both, depending on the loan terms and applicable requirements.
If your EMI remains unchanged while the interest rate rises, a greater share of the payment may go towards interest. The principal may reduce more slowly, and the repayment period may increase.
Review any interest-rate reset communication sent by your lender. If the revised repayment schedule is unclear, request a written explanation.
3. Earlier EMIs Were Missed or Paid Late
A missed EMI can leave an unpaid amount in the account. Depending on the agreement and applicable rules, interest may continue to accrue on the outstanding amount, and applicable overdue or penal charges may also affect the total payable.
Even after you resume regular payments, the account may need to clear earlier arrears and charges before the principal begins reducing as expected.
Ask the lender for a breakdown of overdue instalments, interest and charges. Do not rely only on the total amount displayed in a mobile banking application.
4. Charges Have Been Added to the Account
Your outstanding amount may include charges relating to a payment failure, overdue instalment or another event permitted under the applicable loan terms and rules.
Ask the lender to identify each charge, the date it was applied and the contractual or regulatory basis for it. RBI’s guidance on penal charges is relevant when reviewing whether a charge has been applied in accordance with the lender’s policy and applicable requirements.
A charge that appears incorrect should be disputed in writing. Do not treat every additional amount as valid without checking its basis.
5. Your Payments Have Not Been Credited Correctly
A payment may take time to reflect in a statement, or a transaction may have been allocated incorrectly. A payment made to the wrong loan account, a failed payment later reversed or an unresolved reconciliation issue can create a mismatch.
Compare your bank statement, payment receipts and lender statement. If the payment was deducted from your bank account but is missing from the loan account, raise a written complaint and provide the transaction reference.
6. The Loan Terms Differ From Your Understanding
The repayment period, interest calculation method, reset terms and treatment of unpaid dues can affect how the balance changes. If you have taken a top-up, used a revolving credit facility or modified your repayment arrangement, the current balance may also reflect those changes.
Check the sanction letter, loan agreement, Key Facts Statement where applicable, and the latest repayment schedule before drawing conclusions.
How to Check Whether Your Loan Balance Is Correct
Before considering debt settlement, establish whether the outstanding amount is accurate. A clear record can help you identify a genuine accounting issue or understand why the loan is taking longer to repay.
Step 1: Download Your Latest Loan Statement
Obtain the statement for the full period in which you noticed the problem, not just the latest month. It should help you review payments received, interest debited, charges, overdue amounts and the outstanding principal.
If the lender provides separate statements for the loan account and overdue dues, request both.
Step 2: Compare the Statement With Your Bank Records
Match every EMI with the corresponding bank debit or payment receipt. Note the date, amount, transaction reference and whether the payment was successful or reversed.
If the bank account shows a debit but the lender has not credited it, highlight the specific transaction in your complaint.
Step 3: Review the Principal and Interest Split
Check how much of each EMI was allocated towards interest and how much reduced the principal. Compare these figures with the repayment schedule and any revised schedule issued after an interest-rate change.
Do not compare only the total EMI with the total balance. The important question is whether the lender has applied the payment correctly under the loan terms.
Step 4: Ask for a Written Calculation
Request a detailed calculation of the current outstanding amount, including:
- Opening principal balance
- Interest rate and interest charged
- EMI payments received
- Principal adjusted against each payment
- Overdue amounts and applicable charges
- Any reversals, adjustments or other debits
- Closing principal and total amount payable
This breakdown will make it easier to identify unexplained differences.
Step 5: Raise a Formal Dispute if Necessary
If the calculation does not match your records, submit a complaint through the lender’s official grievance channel. Attach the relevant statements, payment receipts and a short explanation of the discrepancy.
Keep the complaint reference number and all written replies. If the lender does not resolve the complaint satisfactorily, you may consider the applicable escalation process, including the RBI Integrated Ombudsman Scheme where the lender and complaint are eligible and the scheme’s conditions are met.
Do not stop paying an otherwise undisputed EMI solely because you have raised a complaint. If you cannot afford the payment, communicate your financial difficulty separately and request an appropriate arrangement.
What If Your Balance Is Correct but You Cannot Keep Up With Payments?
Sometimes the lender’s calculation is correct, but the loan has become difficult to manage because of reduced income, higher household expenses, medical costs or several existing debts. In this situation, focus on the affordability of the repayment plan.
The right option depends on your income, the loan terms, the amount outstanding and whether you can reasonably repay the debt.
Option 1: Continue Regular Repayment
If your income is stable and the principal is reducing according to the schedule, continuing repayment may be the least disruptive option.
Review your monthly budget and check whether you can make additional principal payments without exhausting your emergency savings or missing essential expenses. Confirm with the lender how any extra payment will be adjusted and whether charges or conditions apply.
Option 2: Request Loan Restructuring
If your current EMI is too high, ask the lender whether it offers a suitable restructuring or repayment modification option.
Depending on the lender’s policy and your circumstances, a possible arrangement may involve a revised tenure, instalment amount or other permitted change to the repayment terms. Approval is not automatic, and a longer tenure may increase the total interest payable.
Before accepting an offer, compare the revised EMI, total repayment amount, tenure and any applicable charges. Request the revised terms in writing.
Option 3: Review Other Debt-Management Options
If you have several loans or credit card balances, list them together and calculate the total monthly obligation. Check whether a suitable consolidation product or another repayment arrangement would genuinely lower your overall cost.
Do not take a new loan simply to make the current EMIs unless you have compared the interest rate, fees, repayment period and total cost. Replacing one unaffordable payment with another expensive obligation can deepen the problem.
Option 4: Consider Debt Settlement
Debt settlement involves negotiating with a lender to accept an agreed amount towards resolving the debt, potentially less than the total contractual amount due. It may be considered when financial hardship makes repayment under the original terms unsustainable.
For eligible regulated lenders, RBI’s framework recognises compromise settlements, subject to the applicable regulatory requirements and the lender’s approved policy. However, settlement is not a borrower’s automatic right. The lender assesses the case and decides whether to approve a proposal.
If you are exploring Personal Loan Settlement, prepare an accurate account of your income, essential expenses, other debts and the amount you can realistically arrange. Do not promise a payment that you cannot make.
Obtain written confirmation of the approved amount, payment deadline, treatment of the remaining dues and the conditions for closure before paying. A verbal assurance from a representative is not a substitute for an authorised settlement agreement.
When Is Loan Settlement Worth Considering?
Settlement deserves consideration when the problem is not merely a confusing statement but a persistent inability to repay the debt.
It may be relevant if:
- Your income has fallen substantially or your employment has ended.
- Essential household expenses leave insufficient funds for the agreed instalments.
- Multiple debts have become unmanageable despite reasonable budgeting.
- The lender’s available repayment options do not make the debt affordable.
- You can arrange the proposed settlement amount without taking on another unsustainable loan.
By contrast, if your balance is increasing because a payment has not been credited or a charge is disputed, resolve that issue first. Settlement should not be used to bypass a calculation that needs correction.
Before deciding, compare the cost and consequences of continued repayment, restructuring and settlement. Consider the effect on your credit record, your ability to arrange the required funds and any legal proceedings or security connected with the loan.
Practical Example: A Borrower Whose Principal Is Barely Reducing
Consider Amit, a salaried employee in Pune with a personal loan. He pays an EMI of ₹15,000 each month but notices that the outstanding principal is falling very slowly.
Amit initially assumes the lender has made an error. After requesting his loan statement, he discovers that his floating interest rate increased and that an earlier delayed payment left an overdue amount. Part of his recent payments has been adjusted according to the account’s outstanding dues.
Amit compares the lender’s calculation with his bank records and asks for clarification on the interest-rate change and overdue charges. The lender explains the calculation and corrects one payment entry that had not been reflected properly.
Amit then reviews his budget. Since his current EMI remains difficult to manage, he asks about restructuring and compares the revised repayment cost with his existing loan. He considers settlement only as a separate option if he cannot reasonably sustain repayment.
This example shows why borrowers should first identify the reason for a growing balance. The right solution may be a statement correction, a repayment adjustment or, in a genuine financial hardship case, a negotiated settlement.
How Does Loan Settlement Affect Your Credit Score?
A settlement may be reported differently from a loan that has been repaid in full under the original agreement. Credit Information Companies maintain credit records based on information furnished by lenders, and the status reported for a settled account can affect how future lenders assess your application.
A settled account may be viewed less favourably than an account closed after full repayment. This can make new credit, a credit card or another loan more difficult to obtain, although the actual decision depends on the lender’s assessment and other factors in your credit profile.
Before agreeing to settle, ask how the account status will be reported and obtain the relevant terms in writing. After completing the agreed payments, collect the settlement confirmation and check your credit report for accurate reporting.
If the reported information is incorrect, raise a dispute with the lender and the relevant Credit Information Company. Keep the settlement letter and payment proofs until the account information has been updated correctly.
You can also review Credit Score After Loan Settlement to understand why settlement and full repayment are not treated as identical outcomes.
Documents to Keep During a Loan Balance Dispute or Settlement
Maintain a single folder containing the records needed to verify the amount and document any agreement. Important records include:
- Loan sanction letter, agreement and repayment schedule
- Latest and earlier loan account statements
- Bank statements showing EMI debits
- Payment receipts and transaction references
- Interest-rate revision notices
- Details of overdue amounts and charges
- Written complaints and lender responses
- Income and expense records if you request restructuring or settlement
- Approved settlement letter and proof of payment, if applicable
- Final account-status or closure confirmation issued by the lender
These documents can help you track what was paid, what remains due and whether the lender has fulfilled the agreed terms.
Mistakes to Avoid When Your Outstanding Balance Keeps Growing
Ignoring the statement: Regular EMI payments do not guarantee that every entry is correct. Review the figures and investigate unexplained changes.
Assuming every charge is illegal: Some charges may be permitted under the agreement and applicable rules. Ask for the basis of each charge before disputing it.
Stopping payments without a plan: Doing so may lead to overdue status, additional consequences under the loan terms and adverse credit reporting. If you cannot pay, contact the lender promptly.
Borrowing more to cover existing EMIs: Additional borrowing can increase the total debt unless the new arrangement genuinely improves affordability and cost.
Accepting a verbal settlement offer: Verify the authorised written terms, amount, deadline and treatment of the remaining dues before making payment.
Believing settlement guarantees future credit approval: A settlement does not guarantee that lenders will approve a future loan or that a credit score will recover within a fixed period.
Frequently Asked Questions
1. Why is my outstanding loan balance increasing even though I pay every EMI?
Possible reasons include a higher floating interest rate, unpaid dues from an earlier period, applicable charges, incorrect payment allocation or a mismatch in the statement. Review the principal-interest split and request a detailed calculation from the lender.
2. Is it normal for a personal loan principal to reduce slowly?
It can be normal, especially when a larger share of early EMIs goes towards interest. However, the actual reduction should be consistent with the loan’s interest rate, repayment schedule and account history. Ask for clarification if the figures do not match.
3. Can I challenge an incorrect loan outstanding amount?
Yes. Submit a written complaint to the lender with your statement, bank records, payment receipts and the specific entries you dispute. Keep the complaint reference and escalate through the applicable grievance process if the issue remains unresolved.
4. Can a lender add charges when an EMI is delayed?
Applicable charges may depend on the loan agreement, the nature of the default and the rules governing the lender. Request an itemised explanation and check whether each charge has been applied in accordance with the applicable requirements.
5. Should I settle my loan if the outstanding balance is not reducing?
Not automatically. First check whether the balance is correct and whether repayment or restructuring is practical. Settlement may be worth exploring if genuine financial hardship makes repayment unsustainable and the lender is willing to approve a settlement.
6. Can a bank or NBFC refuse my loan settlement request?
Yes. Settlement is not generally available as a matter of right. The lender evaluates the request under its applicable policy and circumstances. Submitting a request does not mean the lender must accept a reduced amount.
7. Will loan settlement remove my outstanding balance immediately?
The account should be treated according to the written settlement terms and applicable reporting process. Do not assume that submitting a request or making a partial payment closes the account. Complete the agreed payments and obtain written confirmation of the account’s status.
8. Does loan settlement affect my CIBIL score?
A settled account may be viewed less favourably than a loan repaid in full. The effect on a credit score depends on the wider credit history and how the lender reports the account. Check your credit report after settlement and dispute any inaccurate information.
9. What is the difference between loan settlement and loan restructuring?
Restructuring changes the repayment terms, such as the instalment amount or tenure, subject to approval. Settlement is a negotiated arrangement to resolve the lender’s claim on agreed terms, potentially for less than the full contractual amount due. The financial and credit consequences can differ significantly.
10. What should I do if my lender does not explain the growing balance?
Ask for an itemised statement and written calculation through the lender’s official grievance channel. Include the loan account details, relevant dates and evidence of payments. If the complaint is not resolved, consider the next available escalation route, subject to the applicable eligibility requirements.
Make the Next Decision With Clear Numbers
A growing outstanding loan balance needs investigation before it needs a settlement decision. Review the interest rate, payment allocation, overdue amounts and charges. Ask the lender to correct any errors and explain any valid changes in writing.
If the balance is accurate but the repayment obligation has become unaffordable, compare the long-term cost of continuing payments, restructuring and settlement. Understand the credit-reporting implications and never rely on an unconfirmed promise to close a loan.
Settle Loan can help borrowers understand loan settlement options, prepare questions for a lender and assess the next steps in a debt-resolution process. The right decision should be based on verified account information, realistic affordability and written terms—not simply on the fact that the outstanding amount is falling slowly.