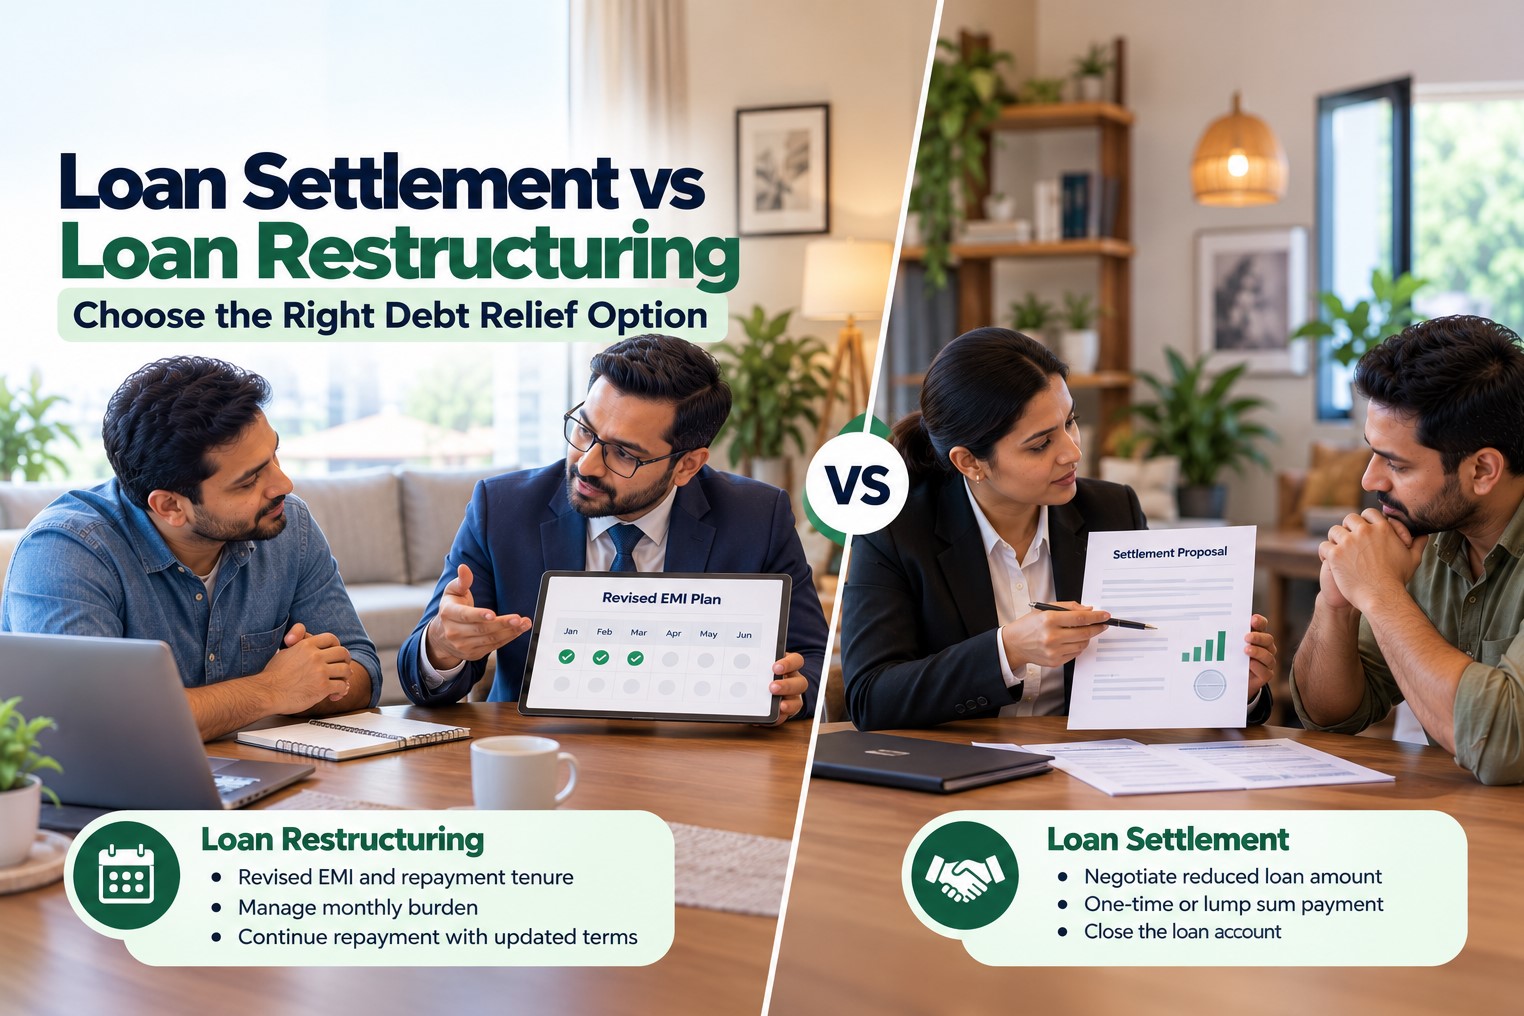
When loan repayments become difficult, loan settlement and loan restructuring are two options borrowers may consider. However, they solve different financial problems. Loan restructuring changes repayment terms, such as the EMI, interest rate, or loan tenure, subject to the lender’s approval. Loan settlement involves an agreement with the lender to accept a specified amount that is less than the total outstanding dues, subject to agreed conditions.
Loan restructuring may suit borrowers who can repay their debt if the terms become more manageable. Loan settlement may be considered when a borrower faces serious financial hardship and cannot realistically repay the full outstanding amount. Neither option is automatically available, and the lender must assess the individual case.
The right choice depends on your income, essential expenses, savings, outstanding debt, repayment history, loan type, and ability to meet future payments. You should also consider the effect on your credit report, the total cost of repayment, and any legal action or security attached to the loan.
Before choosing either option, review your budget and contact the bank or Non-Banking Financial Company (NBFC). A lower EMI does not always mean a cheaper loan, and a reduced settlement amount does not mean that settlement is always the better financial decision.
Loan Settlement vs Loan Restructuring: The Main Difference
The most important difference is what happens to your repayment obligation.
With loan restructuring, the lender modifies the existing repayment terms under an approved arrangement. You generally continue repaying the debt under the revised schedule. Depending on the agreement, this may involve a longer tenure, revised instalments, or other changes.
With loan settlement, the lender agrees to accept a specified amount that is lower than the total amount contractually due. The agreement must clearly state the amount, payment deadline, and conditions. A settlement can reduce the amount you need to pay under the agreement, but it can also affect your credit history and future borrowing options.
| Factor | Loan Restructuring | Loan Settlement |
|---|---|---|
| Main purpose | Make repayment more manageable | Resolve debt when full repayment is not realistically possible |
| Amount payable | Depends on the revised terms; the principal may remain payable | A lender-approved amount may be lower than the total dues |
| EMI | May reduce, increase, or change according to the revised schedule | Usually replaced by the agreed settlement payment or schedule |
| Loan tenure | May be extended or otherwise revised | Depends on the settlement agreement |
| Interest cost | May increase over time if the tenure is extended | Depends on the agreed settlement amount and any stated charges |
| Credit report | Reporting depends on the lender, account status, and applicable reporting rules | May be reported as “settled” rather than “closed” |
| Approval | Subject to the lender’s assessment and policy | Subject to the lender’s approval and settlement policy |
| Suitable situation | Repayment is possible under revised terms | Full repayment is not feasible despite reviewing available alternatives |
The exact outcome depends on the loan agreement, the lender’s policy, and the terms approved for your account. Neither option guarantees a particular credit score or a future loan approval.
What Is Loan Restructuring?
Loan restructuring is an arrangement in which a lender changes certain repayment terms because the borrower is experiencing financial difficulty or the existing schedule has become unmanageable. The objective is to make repayment more sustainable where the borrower’s financial position supports a revised plan.
For example, a borrower who has lost part of their income may be unable to afford a monthly EMI of ₹18,000 but may be able to pay ₹11,000 after adjusting household expenses. The lender may examine whether a longer tenure or another permitted change can make repayment feasible.
Possible changes, where permitted and approved, include:
- Extending the repayment period.
- Revising the instalment amount.
- Changing the applicable interest terms.
- Rescheduling payments.
- Other changes allowed under the lender’s policy and applicable regulatory requirements.
These changes are not automatic. A lender may reject a proposal if the borrower’s income is insufficient, the account does not qualify, or the proposed plan is unlikely to succeed.
When Can Loan Restructuring Make Sense?
Restructuring may be worth discussing if your financial difficulty is temporary or your income has reduced but remains sufficient to support future repayments.
It may be relevant when:
- You have recently changed jobs and your income is temporarily lower.
- A medical expense has disrupted your monthly budget.
- Your business is facing a short-term cash-flow problem but remains viable.
- Your existing EMI is too high, although your income can support a revised repayment schedule.
- You can repay the debt over a longer period without compromising essential household expenses.
Before agreeing, compare the proposed EMI with the total amount payable over the revised tenure. A smaller EMI may increase the total interest cost because the debt remains outstanding for longer.
Ask the lender for the revised repayment schedule, applicable interest terms, charges, treatment of overdue amounts, and credit-reporting implications in writing.
What Is Loan Settlement?
Loan settlement is an arrangement in which a lender agrees to accept a specified amount that is less than the total outstanding contractual dues. It is generally considered when a borrower has serious repayment difficulties and cannot reasonably pay the full amount.
Settlement may be discussed for eligible personal loans, credit card dues, and certain other loan accounts. However, the availability of settlement depends on the lender’s policy, the account’s circumstances, and its assessment of the borrower’s financial condition.
For example, suppose a borrower has total outstanding dues of ₹3,00,000. After reviewing the borrower’s financial hardship, the lender agrees in writing to accept ₹1,80,000 under a settlement arrangement. If the borrower meets all the agreed conditions, the account is handled according to that agreement and the lender’s applicable reporting process.
This is only an illustration, not a standard settlement percentage. There is no universal rule requiring banks or NBFCs to settle every account at a fixed discount.
When Can Loan Settlement Be Considered?
Settlement may be considered when your financial difficulty is severe and you cannot afford the full contractual repayment despite reasonable budgeting.
Examples include:
- Long-term unemployment or a substantial loss of income.
- A serious medical emergency that has depleted your savings.
- Business closure or a major, sustained loss of income.
- Multiple overdue debts that cannot realistically be repaid in full.
- A prolonged inability to meet the original repayment schedule.
Before pursuing settlement, calculate how much you can actually arrange without borrowing more money or sacrificing essential expenses. Do not accept a settlement offer simply because the immediate payment appears smaller than the original debt.
If you are exploring loan settlement options, review the written offer carefully. It should identify the account, settlement amount, payment deadline, instalment conditions if any, and how the lender will treat the remaining dues after successful completion.
Which Option Fits Your Financial Situation?
Instead of choosing based only on the amount you need to pay today, assess your ability to maintain payments over the coming months.
A. Choose restructuring if repayment is still possible
Restructuring may be more appropriate when you have a stable or recoverable source of income and can meet a revised EMI. The key question is whether you can sustain the new schedule until the debt is repaid.
For example, a salaried employee whose monthly income has fallen from ₹60,000 to ₹45,000 may still be able to repay a loan if the lender approves a manageable change in the schedule. The borrower should calculate essential expenses and all other EMIs before proposing an amount.
B. Consider settlement discussions if full repayment is not feasible
Settlement may be worth exploring if the income loss is prolonged, savings are exhausted, and even a revised EMI would be unaffordable.
For example, a small business owner who has closed their business and has no immediate replacement income may be unable to commit to monthly repayments. The borrower can document the financial hardship and ask the lender whether a settlement proposal can be considered.
Approval is not guaranteed. The borrower should also check whether any secured asset, guarantor, co-borrower, legal notice, or recovery proceeding affects the situation.
C. If neither option is affordable
Do not promise an EMI or settlement payment that you cannot meet. Prepare a realistic budget, list all debts, and contact the lenders to discuss available options. Where several accounts are involved, prioritise essential living costs and understand the consequences of each proposed arrangement before signing.
You may also seek qualified financial or legal advice if the debt involves secured property, a guarantor, court proceedings, or disputed charges.
How Do These Options Affect Your Credit Score and Report?
Credit reporting is an important difference between settlement and restructuring, but the effect depends on the lender’s reporting and the account’s history.
Credit impact of restructuring
Restructuring does not automatically protect your credit score. Missed payments before approval may already have affected your credit history. The lender may also report the revised arrangement and account status according to applicable rules and reporting practices.
Ask the lender how the arrangement will be reported to Credit Information Companies (CICs), including TransUnion CIBIL and other authorised credit bureaus. Do not assume that restructuring will make previous late payments disappear.
Credit impact of settlement
When a lender accepts less than the full contractual dues, the account may be reported as “settled” rather than “closed.” A settled status can be viewed less favourably by future lenders because the original obligation was not repaid in full. This can make a future loan or credit card application more difficult, although no single status guarantees approval or rejection.
A “closed” account generally indicates that the contractual dues were paid in full, whereas “settled” indicates that the lender accepted a lesser amount under an agreement. Check your credit report after the lender has processed the arrangement. If the reported information is incorrect, raise a dispute with the credit bureau and the lender.
For more guidance on rebuilding your credit profile, review the steps involved in credit score improvement after loan settlement. Consistent payments on future credit obligations, responsible credit use, and correcting inaccurate report entries can help over time. No specific score increase or recovery timeline can be guaranteed.
RBI Guidelines: What Borrowers Should Know
The Reserve Bank of India (RBI) has issued regulatory instructions relating to the resolution of stressed loan accounts and compromise settlements. Its Framework for Compromise Settlements and Technical Write-offs, issued on 8 June 2023, sets out requirements for regulated entities, including banks and NBFCs, to maintain board-approved policies and follow specified approval processes for compromise settlements.
This does not mean that every borrower has a right to demand a settlement or that a lender must accept a particular offer. Lenders assess cases under their applicable policies and regulatory requirements.
Restructuring arrangements are also subject to the relevant regulatory framework, lender policy, loan type, and account circumstances. The applicable requirements can differ across types of regulated entities and facilities.
Keep these points in mind:
- RBI rules do not create a universal settlement percentage for all loans.
- A lender’s decision depends on its policy, the borrower’s circumstances, and the applicable requirements.
- A request for restructuring or settlement does not automatically stop recovery action or legal proceedings.
- A lender’s approval and the final terms should be documented in writing.
- A technical write-off is not the same as a borrower’s settlement or waiver of the debt.
If you receive a demand notice or legal communication, do not ignore it while negotiating. Seek qualified advice where necessary and respond within any applicable deadline.
Documents to Prepare Before Approaching the Lender
A clear, evidence-based proposal is more useful than a general statement that you cannot pay.
Prepare the documents relevant to your situation:
- Recent salary slips, bank statements, or proof of income.
- Termination letter, salary reduction letter, or other evidence of job-related hardship, if applicable.
- Medical bills or records of major emergency expenses, where relevant.
- Business financial records or evidence of reduced business income, if applicable.
- A list of monthly household expenses and existing EMIs.
- Loan statements showing principal, interest, overdue amounts, and charges.
- Copies of previous communications, notices, and repayment arrangements.
Do not share sensitive financial documents with an unverified intermediary. Confirm the lender’s official process and retain copies of everything submitted.
A Practical Decision Checklist
Before agreeing to either option, answer these questions:
- Is my income likely to recover, or is the financial problem expected to continue?
- After paying essential expenses, how much can I afford each month?
- Can I maintain the proposed EMI throughout the revised tenure?
- If considering settlement, can I arrange the agreed amount without taking another high-cost loan?
- Have I compared the total cost, including interest and permitted charges?
- Do I understand how the lender will report the account to credit bureaus?
- Have I received the complete offer and conditions in writing?
- Is the loan secured, guaranteed by another person, or already subject to legal proceedings?
If you can repay the debt under realistic revised terms, restructuring deserves serious consideration. If full repayment is not feasible, settlement discussions may be relevant, but the credit and legal consequences should be understood before you proceed.
Common Mistakes Borrowers Should Avoid
Choosing only by the EMI: A lower EMI can extend the repayment period and increase the total cost. Compare the full schedule, not just the monthly amount.
Assuming settlement is guaranteed: Banks and NBFCs are not required to accept every settlement proposal. Do not make financial commitments based on verbal assurances.
Ignoring credit reporting: Ask how the account will be reported after completion and keep the written response.
Paying an intermediary without verification: No agent can guarantee that a lender will approve a settlement. Verify authorisation and payment instructions directly with the lender.
Relying on verbal promises: Confirm the approved amount, due dates, and consequences of non-payment in writing before paying.
Ignoring notices: Negotiations do not automatically suspend legal or recovery processes. Address notices within the applicable deadlines and seek legal advice when needed.
Frequently Asked Questions
1. Is loan settlement better than loan restructuring?
Neither option is better for every borrower. Restructuring may suit someone who can repay the debt under revised terms. Settlement may be considered when full repayment is not feasible because of serious financial hardship. Compare affordability, total cost, credit reporting, and legal circumstances before deciding.
2. Can I request loan restructuring before missing an EMI?
You can contact your lender before a missed payment and ask whether any suitable arrangement is available. Approval depends on the lender’s policy and your circumstances. Early communication can help you understand the options before overdue amounts accumulate, but it does not guarantee approval.
3. Does loan restructuring reduce the principal amount?
Not necessarily. Restructuring commonly changes repayment terms, such as instalments or tenure. Any reduction in principal would depend on a specific arrangement approved by the lender. Ask for a written breakdown of the revised principal, interest, charges, and total repayment amount.
4. Can a bank reject my loan settlement request?
Yes. Settlement is subject to the lender’s assessment, policy, and applicable regulatory requirements. The bank or NBFC may reject the offer or propose different terms. You should not assume that a particular level of overdue debt makes settlement compulsory.
5. Will a settled loan remain on my CIBIL report?
Credit account information is reported by lenders to Credit Information Companies under applicable reporting requirements. A settled status may remain visible in your credit history according to the bureau’s records and applicable retention practices. Check your current report for the account status and raise a dispute if information is inaccurate.
6. Can I get another loan after settlement?
You can apply, but approval is not guaranteed. Lenders may consider the settled status, payment history, income, current obligations, and their own credit policies. A settled account can make borrowing more difficult than an account repaid in full.
7. Does restructuring stop recovery calls or legal action?
Do not assume that it does. The effect depends on the approved arrangement, applicable law, and the status of any recovery or legal process. Obtain written confirmation of what the lender has agreed to and respond to formal notices appropriately.
8. Is a loan write-off the same as loan settlement?
No. A write-off is an accounting treatment used by a lender and does not by itself mean the borrower’s obligation has been waived. Settlement is an agreement under which the lender accepts specified payment terms. Confirm the actual account status and any remaining obligations with the lender.
9. Can I settle a credit card balance as well as a personal loan?
You may ask the card issuer or lender about available options, but eligibility and approval vary. Review the outstanding amount, fees, interest, repayment ability, and credit-reporting consequences before agreeing. For account-specific guidance, explore credit card loan settlement and confirm the terms directly with the issuer.
10. What should I do if I cannot afford either option?
Prepare a realistic income-and-expense statement, list all outstanding debts, and contact each lender to discuss possible arrangements. Avoid taking expensive new credit to make an unsustainable payment. If the account involves a secured asset, guarantor, disputed debt, or legal notice, consider qualified financial or legal advice.
Final Thoughts
The decision between loan settlement and loan restructuring should be based on what you can realistically afford, not on which option sounds easier at first.
Restructuring may be appropriate when your income can support repayment under revised terms. Settlement may be considered when serious financial hardship makes full repayment impractical, but it can have consequences for your credit history and future borrowing.
Start by reviewing your finances, obtaining the latest loan statement, and contacting the lender through its official channels. Compare the total repayment cost, understand the credit-reporting implications, and insist on written terms before making a payment.
If you need help understanding your available options, Settle Loan can help you review the loan settlement process and prepare questions for discussion with your lender. The final decision and approval remain subject to the lender’s policies, the applicable law, and the facts of your case.