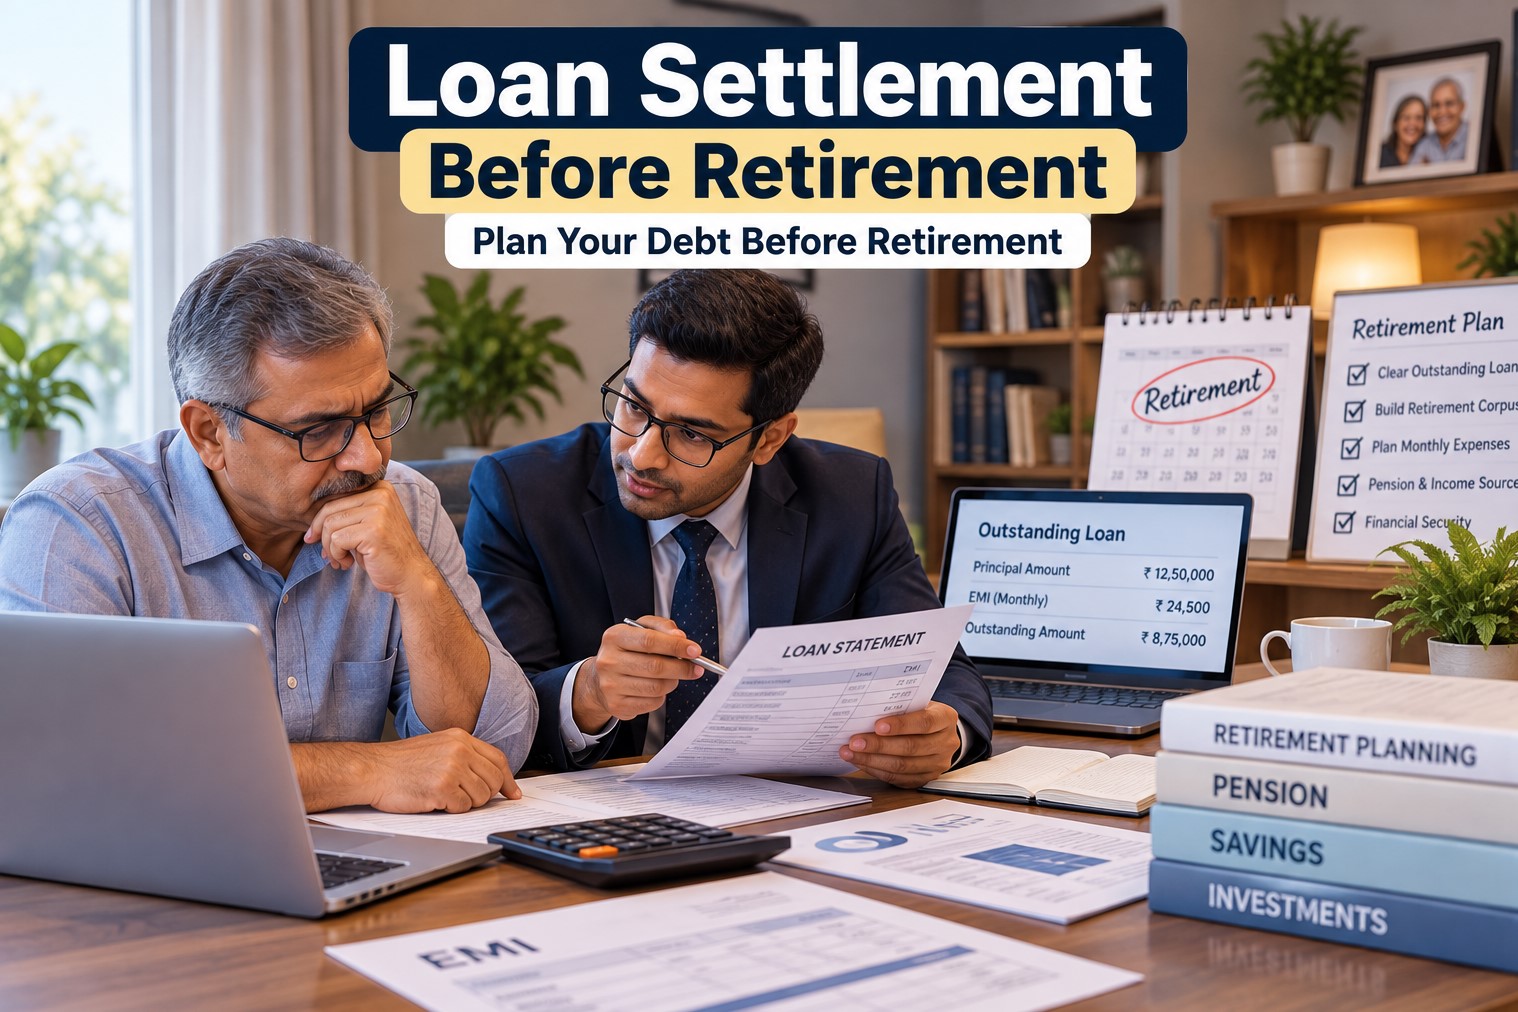
Retirement changes the way a borrower should look at outstanding debt. During employment, a regular salary may support an EMI even when the loan has a long remaining tenure. After retirement, income may come mainly from pension, investments, rental income, business income or accumulated savings. If a large EMI continues during this period, it can put pressure on the entire retirement plan.
For this reason, borrowers approaching retirement should review outstanding loans well before their expected retirement date. Loan settlement before retirement may be considered when full repayment is no longer realistically affordable, but it is not an automatic right and should not be confused with ordinary loan closure.
A practical retirement debt review should answer four questions:
- Can the loan be fully repaid before retirement?
- If not, can the EMI continue comfortably after retirement?
- Is restructuring or another repayment arrangement available?
- If genuine financial hardship exists, would the lender consider a negotiated settlement?
The right answer depends on income, assets, loan terms, outstanding balance, retirement benefits and the lender’s policies.
Why Outstanding Debt Becomes More Important Near Retirement
A loan taken at age 35 or 40 may have been manageable because the borrower had several years of employment income ahead.
The situation can look different at age 58 or 59.
Suppose a borrower earns ₹1.2 lakh per month and pays ₹30,000 toward EMIs. During employment, the EMI may be manageable. After retirement, monthly income may fall to ₹55,000 from pension and other predictable sources.
The same ₹30,000 EMI would consume more than half of that regular income.
This is why retirement planning should include a detailed review of debt rather than focusing only on investments and savings.
A borrower should consider:
- Remaining loan principal
- Remaining tenure
- Current EMI
- Interest rate
- Expected retirement income
- Pension
- Provident Fund or other retirement benefits
- Regular household expenses
- Medical and insurance costs
- Existing credit card or other debt
- Emergency fund
- Dependents
- Any secured asset linked to the loan
The aim is to understand whether the loan will remain affordable after employment income ends.
Should You Become Debt Free Before Retirement?
Being debt free before retirement can reduce monthly financial obligations, but paying off every loan before retirement is not automatically the correct decision for every borrower.
For example, using almost all retirement savings to close a relatively low-cost loan may leave the borrower with very little emergency liquidity.
On the other hand, carrying a large high-cost unsecured loan into retirement may create significant monthly pressure.
Therefore, the decision should consider both sides:
Debt reduction: Lower EMI obligations and fewer repayment risks.
Liquidity: Enough savings to handle healthcare, household expenses and unexpected events.
A financially sound retirement plan generally needs a balance between reducing debt and retaining sufficient accessible funds.
The First Step: Create a Retirement Debt Statement
Before considering settlement, prepare a simple loan-wise statement.
For each loan, record:
- Lender name
- Loan type
- Original amount
- Current outstanding principal
- Current EMI
- Interest rate
- Remaining tenure
- Number of EMIs remaining
- Current overdue amount, if any
- Prepayment or foreclosure terms
- Security or collateral involved
- Co-borrower or guarantor details
- Current account status
Do not rely only on old sanction letters.
Ask the lender for an updated statement because the current outstanding amount may be different from the balance you remember.
This exercise often reveals that some loans can be comfortably completed before retirement while one particular loan is creating most of the financial pressure.
That loan may then deserve separate attention.
Three Possible Paths Before Retirement
A borrower approaching retirement generally needs to compare three broad approaches.
Continue Normal Repayment
If the borrower has sufficient income and the loan will be completed within a reasonable period, continuing regular EMI payments may be the simplest option.
This may be particularly relevant when:
- Income is stable.
- Retirement savings are limited.
- The loan has a manageable interest cost.
- The EMI will remain affordable after retirement.
- The remaining tenure is short.
There is no reason to pursue settlement simply because retirement is approaching.
Restructure or Modify the Repayment
If the borrower expects difficulty after retirement but can still repay over a longer period, it may be useful to ask the lender about available restructuring or other repayment options.
RBI’s framework on resolution of stressed assets recognises restructuring as a resolution approach where lenders provide concessions because of a borrower’s financial difficulty. The exact availability and terms depend on the lender, loan category and applicable framework.
A restructuring arrangement may alter repayment terms rather than ending the liability.
This can be relevant when the borrower has predictable post-retirement income but needs a lower monthly repayment burden.
Consider Loan Settlement
Settlement becomes more relevant when the borrower cannot realistically repay the full dues and has genuine financial hardship.
RBI’s 2023 framework recognises compromise settlements as negotiated arrangements between regulated entities and borrowers, subject to the lender’s Board-approved policy and applicable requirements. It does not establish one universal settlement percentage for every borrower.
For someone nearing retirement, settlement should therefore be considered as a resolution option, not as a guaranteed retirement-planning shortcut.
When Can Loan Settlement Before Retirement Be Relevant?
A borrower may consider discussing settlement with the lender when several of these circumstances exist:
- Income has permanently reduced.
- Retirement is approaching and post-retirement income will not support the existing EMI.
- The borrower has already missed payments.
- Multiple loans are creating an unsustainable repayment burden.
- Savings are insufficient to clear the entire debt.
- A business or professional income source has declined significantly.
- The borrower has substantial essential expenses.
- There is no realistic path to maintaining the current repayment schedule.
The lender will still assess the account and decide whether a settlement can be approved.
Simply reaching retirement age does not create an automatic right to settle a loan.
A Simple Example: Salaried Borrower Near Retirement
Consider a 58-year-old employee with:
- Monthly salary: ₹1.1 lakh
- Personal loan EMI: ₹24,000
- Home-related EMI: ₹18,000
- Retirement expected in two years
- Expected post-retirement income: ₹55,000 per month
The borrower may be able to pay ₹42,000 in EMIs while earning ₹1.1 lakh.
But after retirement, the same EMIs could consume a large part of the expected monthly income.
The borrower should not wait until retirement to address the issue.
A sensible review could involve:
- Checking which loan will end first.
- Reviewing whether any loan can be prepaid without exhausting essential savings.
- Asking lenders about repayment modification where appropriate.
- Building an emergency reserve.
- Assessing whether the remaining debt is affordable after retirement.
- Considering settlement only if full repayment is genuinely unrealistic.
The important point is that the borrower has several possible routes. Settlement is only one of them.
What If Retirement Is Only Months Away?
When retirement is very close, avoid making rushed financial decisions.
A borrower should first identify the money expected to be received at retirement and classify it according to purpose.
For example:
- Emergency reserve
- Medical expenses
- Essential household expenses
- Regular income generation
- Existing debt repayment
- Planned large expenses
Using the entire retirement corpus to close loans can create a different financial risk.
At the same time, using retirement funds to make a large payment without obtaining a formal loan closure or settlement document can create serious problems.
If settlement is being considered, the borrower should obtain the approved terms in writing before transferring funds.
What Documents Should Borrowers Collect?
A retirement debt review should be document-based.
Keep copies of:
- Latest loan statements
- Sanction letters
- Loan agreements
- EMI schedules
- Bank statements
- Income proof
- Pension estimates, where available
- Retirement benefit details
- Investment and savings statements
- Insurance details
- Credit report
- Communication from lenders
- Overdue notices
- Settlement proposals, if any
- Legal notices, if received
If a borrower is already in default, documentation becomes even more important.
It helps establish the actual account position and prevents decisions based on incomplete information.
Do Not Ignore Overdue Charges
Borrowers sometimes notice that the outstanding amount has increased because of overdue amounts and applicable penal charges.
RBI’s Fair Lending Practice framework requires regulated entities to follow rules around penal charges. Penal charges are intended to promote credit discipline and should not be used as an additional revenue-enhancement component. RBI also requires applicable penal charges and their reasons to be communicated in relevant borrower communications.
This does not mean that a borrower can simply remove every overdue amount from the account.
Instead, obtain the latest statement and understand how the outstanding figure has been calculated.
If there is a genuine discrepancy, raise it with the lender through the appropriate channel.
How Settlement Can Affect a Retirement Financial Plan
Settlement can potentially reduce the amount needed to resolve an unaffordable account, but it can also have consequences that continue beyond the immediate payment.
Before accepting a settlement, consider:
Credit history
The account’s settlement status can affect how future lenders view the borrower’s credit history. Credit Information Companies receive information from their reporting members, so borrowers should understand the credit-reporting implications before choosing settlement.
Future borrowing
A borrower who settles may find future access to credit more difficult or subject to different terms. RBI’s compromise settlement framework also provides for a cooling period before regulated entities can assume fresh exposures to borrowers subject to compromise settlements, with a minimum floor of 12 months for non-farm exposures, subject to the framework and lender policy.
Retirement liquidity
The settlement amount should not be considered in isolation.
Ask:
“After paying the settlement amount, will I still have enough money for essential retirement expenses and emergencies?”
This question is often more important than simply asking how much the lender is willing to reduce.
Secured Loans Need Extra Care
A personal loan and a secured loan should not be treated in exactly the same way.
If a loan is backed by property or another asset, the borrower must understand the consequences of non-payment and settlement for the security.
For personal loans, RBI directions require regulated entities to release original movable or immovable property documents and remove registered charges within 30 days after full repayment or settlement of the loan account, subject to the applicable directions. Where delay is attributable to the lender, the prescribed compensation can apply.
For any secured borrowing, the borrower should confirm exactly what happens to the collateral after settlement and obtain the required documentation.
Do not assume that making a payment automatically removes every charge or security interest.
What About a Joint Loan or Guarantor?
Retirement planning becomes more complicated if another person is connected to the loan.
This can include:
- Joint borrower
- Co-applicant
- Guarantor
- Family member whose property is used as security
Before settlement or restructuring, check how the proposed arrangement affects every party.
A borrower should not assume that settlement of one person’s obligation automatically removes all obligations of a co-borrower or guarantor.
Where the account has legal proceedings or security interests, professional legal advice may be appropriate.
A Practical Pre-Retirement Loan Checklist
Use this checklist at least several months before retirement:
Step 1: List every debt
Include personal loans, home loans, vehicle loans, credit cards and other liabilities.
Step 2: Calculate post-retirement income
Use realistic figures rather than assuming current salary will continue.
Step 3: Calculate essential monthly expenses
Include healthcare, insurance, household expenses and support for dependents.
Step 4: Compare EMI with retirement income
Identify which loans may become difficult to service.
Step 5: Check the remaining tenure
A loan ending shortly after retirement is different from one continuing for many years.
Step 6: Review repayment options
Ask the lender whether prepayment, restructuring or another repayment arrangement is available.
Step 7: Assess settlement only where appropriate
If full repayment is genuinely unrealistic, discuss whether the lender has a formal settlement process.
Step 8: Protect your emergency savings
Do not use every retirement rupee for debt repayment without considering future needs.
Step 9: Obtain written documentation
Never depend solely on verbal settlement commitments.
Step 10: Check your credit report afterward
Make sure the lender’s reporting is updated accurately.
Common Mistakes to Avoid Before Retirement
Using the entire retirement corpus to close debt
Debt reduction is important, but having no emergency liquidity can create another financial problem.
Waiting until the last month of employment
Loan planning should begin before retirement, particularly when the remaining tenure extends beyond the expected retirement date.
Assuming settlement means “debt free” in every sense
A settlement can resolve a lender’s claim according to the agreed terms, but it can have credit-reporting and future-borrowing consequences.
Comparing settlement offers only by percentage
A lower settlement amount is not automatically financially better if it leaves the borrower without adequate retirement savings.
Ignoring the credit report
After the account is resolved, borrowers should review the information reported to Credit Information Companies.
Taking expensive new debt to fund settlement
A borrower should calculate the total cost before replacing one liability with another.
Ignoring legal communication
A pending legal proceeding can affect the settlement process. RBI’s compromise settlement framework states that where recovery proceedings are pending before a judicial forum, a settlement may require the concerned judicial authority’s consent decree.
Should You Settle a Loan or Pay It Off Before Retirement?
There is no universal answer.
The decision can be viewed through three questions:
If you can comfortably repay the loan and retain sufficient retirement reserves: continuing repayment may be practical.
If you can repay but the post-retirement EMI will be difficult: ask about restructuring or another repayment arrangement.
If full repayment is genuinely unrealistic because of long-term financial hardship: discuss whether the lender has a formal settlement process.
This approach is more useful than deciding on settlement solely because retirement is approaching.
How to Aim for a Debt-Free Retirement
A debt-free retirement does not necessarily mean paying every lender immediately.
It means creating a financial position where essential expenses can be met without depending on unaffordable debt.
For some borrowers, this may involve completing loans before retirement.
For others, it may involve restructuring a loan so that repayment remains affordable.
For borrowers facing serious financial hardship, Debt Settlement or a formal Loan Settlement arrangement may need to be evaluated.
The important part is to make the decision early enough to understand the consequences.
Frequently Asked Questions
1. Can I settle my loan before retirement?
You can ask the lender to consider a settlement, but approval depends on the lender’s policy, the account and your financial circumstances. Retirement itself does not guarantee settlement.
2. Is it necessary to clear all loans before retirement?
No. The more important question is whether the remaining EMI can be comfortably supported by predictable post-retirement income while maintaining adequate savings for essential expenses.
3. Is loan settlement a good way to become debt free before retirement?
Settlement can be considered when full repayment is genuinely unaffordable, but it has potential credit and future-borrowing consequences. It should be compared with repayment and restructuring options.
4. Can pension income be used to repay an existing loan?
Yes, pension can form part of a borrower’s repayment capacity, subject to the lender’s terms and the borrower’s overall financial position. The borrower should first calculate essential expenses and emergency requirements.
5. Should I use my retirement savings to close my loan?
Not automatically. Compare the benefit of eliminating the EMI against the need to retain funds for healthcare, living expenses and emergencies.
6. Will loan settlement affect my CIBIL report?
Settlement can affect how the account is reported in the borrower’s credit history. Borrowers should understand the reporting implications before accepting settlement and check their credit report afterward.
7. Can I negotiate settlement if I have not yet retired?
You can request a settlement before retirement, but the lender decides whether it will consider and approve the proposal. A borrower should demonstrate the actual financial circumstances rather than assuming retirement alone is sufficient.
8. Is restructuring different from loan settlement?
Yes. Restructuring generally modifies repayment terms so that the borrower can continue servicing the loan. Settlement involves a negotiated arrangement to resolve the lender’s claim under agreed terms.
9. What happens to property documents after settlement of a personal loan?
For applicable personal loans covered by RBI’s responsible lending directions, regulated entities must release original movable or immovable property documents and remove registered charges within 30 days after full repayment or settlement.
10. Can I get another loan after settling a loan?
Future borrowing is not necessarily prohibited, but settlement can affect how lenders assess the borrower. RBI’s compromise settlement framework also provides for a cooling period before fresh exposure by regulated entities, subject to the applicable framework and lender policy.
11. What if I have a loan with a co-borrower or guarantor?
Do not assume that settlement automatically removes every person’s obligation. Review the settlement document and the loan agreement carefully to understand how each borrower or guarantor is affected.
12. When should I start reviewing my loans before retirement?
Ideally, start several months or years before retirement, especially if any loan will continue after your employment income stops. Early review gives more time to compare repayment, prepayment, restructuring and settlement options.
Conclusion
Planning for retirement while carrying outstanding debt requires more than calculating the current EMI. Borrowers should look at the full picture: remaining principal, loan tenure, interest cost, retirement income, essential expenses, emergency savings and the consequences of different resolution options.
For someone who can comfortably repay the loan, normal repayment may remain appropriate. Where retirement income is expected to be lower but repayment is still possible, restructuring or another lender-approved arrangement may be worth exploring. Where genuine financial hardship makes full repayment unrealistic, Loan Settlement Before Retirement can be discussed with the lender.
The objective should not be to settle a loan simply because retirement is approaching. The objective is to create a sustainable financial position for the years after regular employment income ends.
A carefully prepared debt-free retirement plan should therefore consider both sides of the decision: reducing debt and protecting the savings needed to live through retirement with financial stability.