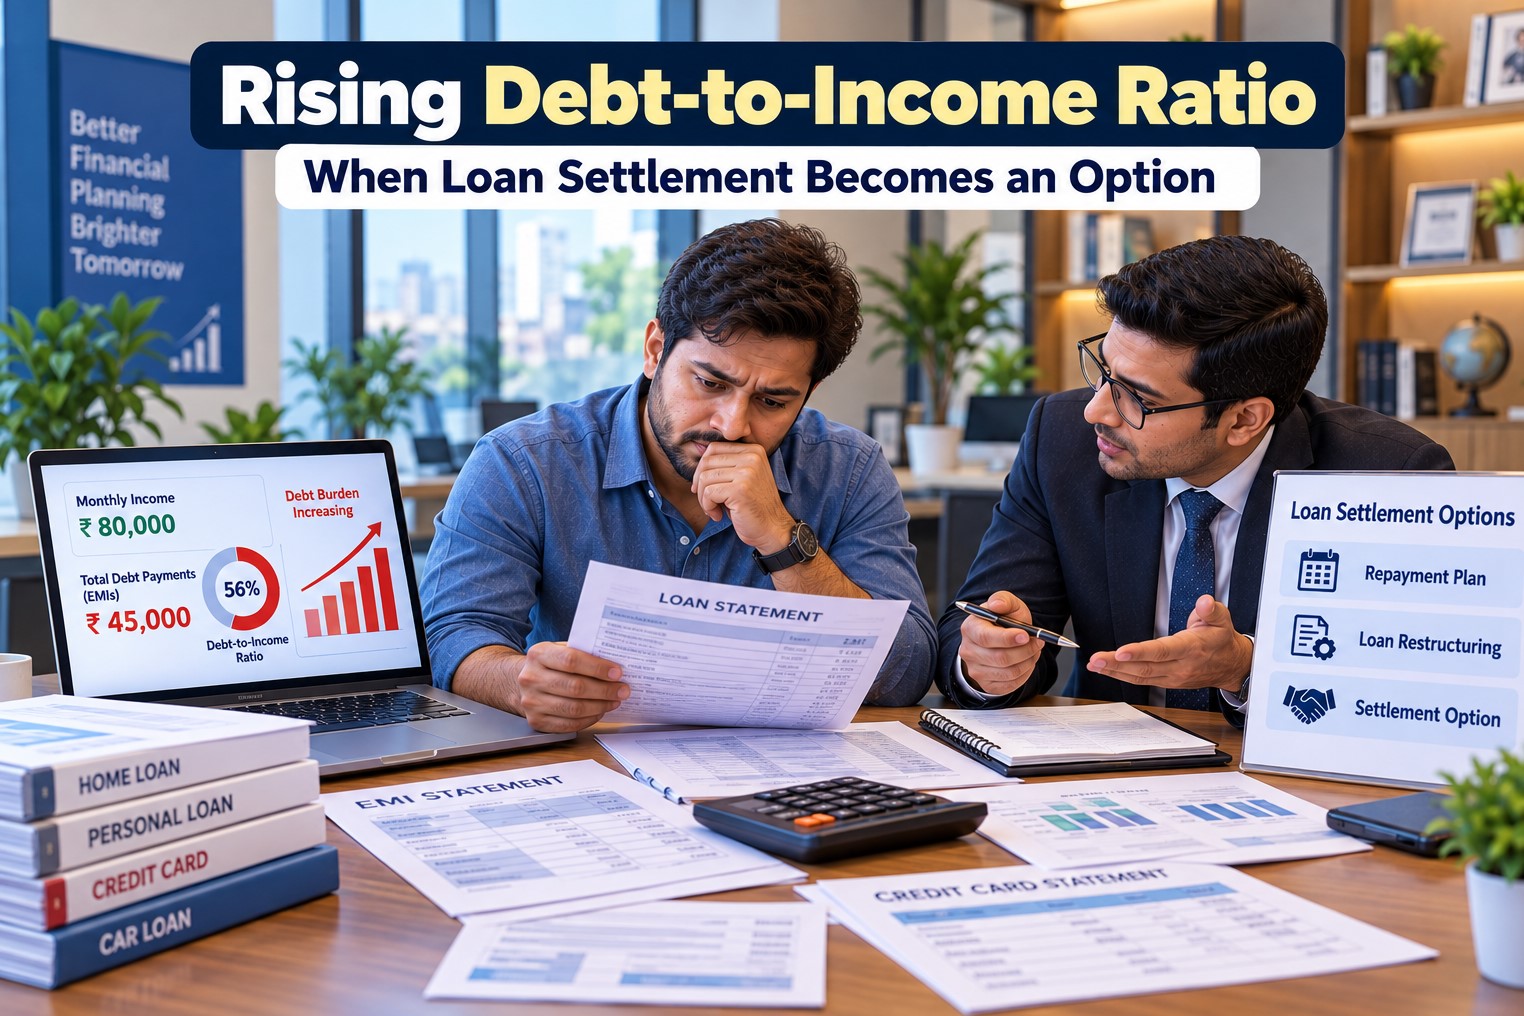
A rising debt-to-income ratio means a larger share of your income is being used to repay debt. In India, this can happen when a borrower takes additional loans, uses credit cards to meet expenses, experiences an income reduction, or continues paying EMIs while essential household costs increase.
A high debt-to-income ratio does not automatically mean you should settle a loan. It is a warning sign that your current debt obligations may be becoming difficult to sustain. The first step is to calculate your actual monthly debt burden and identify why it is increasing.
If the problem is temporary, better budgeting or repayment restructuring may be enough. If the borrower has long-term financial hardship and cannot realistically repay the full outstanding liability, loan settlement may be one option to discuss with the lender.
Settlement is not guaranteed, and it can affect credit history and future borrowing. The decision should therefore be based on actual repayment capacity, outstanding debt, savings, income stability and the lender’s applicable policies.
What Is a Debt-to-Income Ratio?
The debt-to-income ratio, commonly called DTI, compares your monthly debt obligations with your monthly income.
A simple calculation is:
DTI = Total Monthly Debt Payments ÷ Gross Monthly Income × 100
For example, suppose your gross monthly income is ₹80,000 and your total monthly debt payments are ₹32,000.
Your DTI would be:
₹32,000 ÷ ₹80,000 × 100 = 40%
The ratio itself does not decide whether you qualify for a loan or settlement. Different lenders use different credit assessment methods, and some may consider net income, loan type, existing liabilities and other factors.
For a borrower, however, the calculation is useful because it shows how much income is already committed to debt.
Why Does the Debt-to-Income Ratio Keep Rising?
A rising DTI usually has one of two causes:
Debt is increasing, or income is falling.
Sometimes both happen at the same time.
Common reasons include:
- Taking a new personal loan
- Increasing credit card balances
- Using one loan to repay another
- Paying only minimum amounts on credit cards
- Salary reduction
- Job loss
- Business income falling
- Medical or family expenses
- Higher household costs
- Multiple EMIs starting within a short period
- Existing loans running for a long tenure
- Using credit to meet regular living expenses
Consider an employee earning ₹1 lakh per month.
Initially, the borrower has a single EMI of ₹15,000.
Later, a second personal loan adds ₹12,000 and a vehicle loan adds another ₹10,000. Credit card repayments add ₹8,000.
The monthly debt obligation has now increased to ₹45,000.
Even though the salary has not changed, the borrower’s debt burden has increased significantly.
If income then falls to ₹80,000, the financial pressure becomes even stronger.
A Rising DTI Is a Warning Sign, Not a Settlement Trigger
This distinction is important.
There is no universal DTI percentage at which a borrower automatically becomes eligible for loan settlement.
A high ratio should instead prompt a deeper financial review.
Ask:
- Can I pay all EMIs from my regular income?
- Am I using credit cards to pay household expenses?
- Am I borrowing to pay another EMI?
- Do I have emergency savings?
- Has my income changed permanently?
- Are my debts increasing every month?
- Will my income recover soon?
- Are any accounts already overdue?
If the answers indicate that debt is growing faster than repayment capacity, immediate financial action is more important than waiting for the account to deteriorate.
Calculate Your Real Debt Burden
Do not calculate DTI using only your largest loan.
Prepare a complete list of monthly debt payments.
Include:
- Personal loan EMIs
- Home loan EMI
- Vehicle loan EMI
- Education loan EMI
- Business loan repayment
- Credit card payments
- Consumer finance EMIs
- Other formal debt obligations
Then compare these payments with your income.
But there is another calculation that is equally important:
Monthly income – essential household expenses – debt payments = remaining cash flow
A borrower may technically have a manageable DTI but still struggle because essential expenses consume most of the remaining income.
For example:
Monthly income: ₹90,000
Debt payments: ₹30,000
Essential expenses: ₹50,000
Remaining amount: ₹10,000
If an unexpected medical bill or family expense arises, the borrower may quickly fall behind.
Therefore, DTI should be used as a financial warning indicator, not as the only decision-making factor.
What Should You Do When DTI Starts Increasing?
The earlier you identify the problem, the more options you may have.
Step 1: Stop Adding Unnecessary Debt
If your existing debt is already increasing, taking another high-cost loan may make the situation worse.
Avoid borrowing simply to maintain a lifestyle or cover recurring expenses that cannot be supported by your income.
Step 2: List Every Liability
Create a debt sheet with:
- Outstanding amount
- EMI
- Interest rate
- Remaining tenure
- Due date
- Current account status
- Secured or unsecured status
This will show which liabilities are creating the largest monthly burden.
Step 3: Separate Temporary and Permanent Problems
A three-month income disruption is different from a permanent reduction in earning capacity.
If your income is likely to recover, the solution may involve short-term cash-flow management.
If your income has permanently fallen, you may need a more structured debt-resolution strategy.
Step 4: Contact the Lender Before Ignoring Payments
If repayment is becoming difficult, communicate with the lender rather than simply stopping payments.
Ask what repayment or restructuring options may be available under the lender’s policy.
Step 5: Evaluate Settlement Only When Full Repayment Is Unrealistic
If the borrower has genuine financial hardship and cannot realistically repay the full liability, settlement can be discussed with the lender.
When Can Loan Settlement Become Relevant?
Loan settlement may become relevant when the borrower’s financial situation has changed significantly and there is no realistic path to full repayment.
Possible circumstances include:
- Long-term income loss
- Permanent salary reduction
- Business failure
- Multiple unsecured debts
- Persistent EMI defaults
- Large accumulated overdue amounts
- Major unavoidable expenses
- Debt obligations significantly exceeding realistic repayment capacity
However, a high DTI alone does not guarantee settlement.
The lender evaluates the account according to its applicable policies.
RBI’s framework on compromise settlements recognises negotiated settlements between regulated entities and borrowers and requires regulated entities to maintain Board-approved policies for such arrangements. (rbi.org.in)
Loan Settlement vs Restructuring: Which Problem Does Each Address?
These options should not be confused.
| Option | Main purpose | What happens to the debt? |
|---|---|---|
| Repayment | Complete the loan under agreed terms | Borrower continues normal payments |
| Restructuring | Make repayment more manageable | Terms may be modified |
| Loan settlement | Resolve the lender’s claim through negotiation | Settlement terms determine the amount and conditions |
If the borrower can still repay but needs a longer period or modified terms, restructuring may be worth discussing.
If the borrower cannot realistically repay the full liability because of continuing financial hardship, settlement may become relevant.
This distinction prevents borrowers from treating settlement as the first response to every increase in DTI.
What Does RBI Say About Loan Settlement?
RBI’s framework for compromise settlements does not establish one fixed percentage that every borrower can use to settle a loan.
The regulated entity must operate within its approved policy and applicable regulatory requirements.
Therefore, borrowers should be cautious about claims such as:
- “RBI allows 50% settlement for everyone.”
- “A high DTI guarantees settlement.”
- “The bank must waive all interest.”
- “Every overdue loan can be settled at the same percentage.”
These are not universal rules.
The actual terms depend on the lender, loan account, borrower circumstances and applicable policy.
Practical Example: Personal Loan and Credit Card Debt
Consider Neha, who earns ₹70,000 per month.
She has:
- Personal loan EMI: ₹18,000
- Vehicle loan EMI: ₹9,000
- Credit card repayment: ₹10,000
- Consumer loan EMI: ₹6,000
Her monthly debt payments are ₹43,000.
Her DTI based on gross income is approximately 61%.
She also uses her credit card for household expenses because very little cash remains after EMIs and essential expenses.
This is a warning sign.
If her salary is stable and she can reduce spending, she may be able to gradually lower the debt.
If she has suffered a permanent income reduction and cannot maintain repayments, she may need to discuss restructuring or Debt Settlement options.
The key point is that the settlement decision should come after understanding the complete financial position.
What Happens If You Ignore a Rising DTI?
Ignoring a rising debt burden can create a cycle:
Higher borrowing → higher EMIs → lower disposable income → more credit usage → missed payments → overdue amounts → greater financial stress
Once missed payments begin, the situation can become harder to manage.
Overdue accounts may also affect credit reporting.
Credit Information Companies receive credit information from their reporting members. Therefore, repeated missed payments and eventual settlement can have implications for the borrower’s credit profile.
This is one reason borrowers should act when the debt burden starts becoming unsustainable rather than waiting until several accounts are seriously overdue.
Can a Balance Transfer Solve a High DTI?
Sometimes refinancing can reduce interest cost or change repayment terms, but it does not automatically solve a high debt burden.
If the underlying problem is that the borrower has too much total debt relative to income, moving one loan to another lender may not be enough.
A balance transfer may be worth evaluating when:
- The borrower remains financially stable.
- The new lender offers materially better terms.
- The borrower meets eligibility criteria.
- The transfer reduces the total repayment burden.
- There are no hidden costs that eliminate the expected benefit.
But if income is already insufficient to service the total debt, refinancing may only postpone the problem.
Should You Take Another Loan to Pay Existing EMIs?
This deserves particular caution.
A borrower may think:
“Once I take this new loan, I can pay the old EMI.”
But if the new loan adds another EMI, the DTI can rise further.
Before borrowing again, calculate:
Old debt payment + new EMI + all other debt payments
Then compare the result with reliable monthly income.
If the new borrowing only keeps the account current temporarily without improving long-term affordability, it may not be a sustainable solution.
How Does Loan Settlement Affect Credit History?
Settlement can have consequences for a borrower’s credit history.
A settled account is different from an account that was fully repaid according to its contractual terms.
Credit Information Companies use information supplied by lenders, so borrowers should understand how the lender intends to report the account.
This matters if you plan to apply for:
- Home loan
- Vehicle loan
- Personal loan
- Credit card
- Business finance
in the future.
After resolving debt, borrowers can focus on rebuilding financial discipline through timely payments and controlled credit usage. A structured Credit Score Builder approach can be useful during this recovery period.
Documents to Prepare Before Discussing Settlement
If settlement becomes a genuine possibility, prepare evidence that explains your financial position.
Useful documents can include:
- Latest loan statements
- Bank statements
- Salary slips
- Employment termination documents
- Income reduction evidence
- Business financial records
- Other loan statements
- Credit card statements
- Credit report
- Medical expense documents where relevant
- Evidence of major unavoidable expenses
- Previous communication with lenders
The purpose is to present your financial situation accurately.
Do not manufacture or exaggerate financial hardship.
What Should You Check Before Accepting a Settlement?
Never evaluate a settlement proposal only by looking at the discount.
Check:
Settlement amount: How much must actually be paid?
Payment deadline: Can you realistically arrange the money?
Source of funds: Will paying the amount leave you without emergency savings?
Account status: What will the lender report after settlement?
Remaining obligations: Are there any co-borrower, guarantor or security-related obligations?
Legal proceedings: Is there an existing notice or case?
Written confirmation: Does the lender’s document clearly state the agreed terms?
After making the agreed payment, retain receipts and the final documentation.
Common Mistakes When DTI Keeps Rising
1. Treating credit cards as additional income
Credit is not income. Using one credit facility to maintain another debt can increase the total burden.
2. Looking at only one EMI
A ₹15,000 EMI may seem manageable until four other obligations are added.
3. Ignoring income reduction
DTI can increase even when debt remains unchanged if income falls.
4. Applying for many loans
Repeated borrowing can increase financial pressure instead of solving it.
5. Waiting until all accounts become overdue
Early financial review provides more possible options.
6. Assuming settlement is guaranteed
Settlement depends on lender approval.
7. Believing settlement automatically improves credit
Settlement may have adverse credit-reporting consequences.
8. Using retirement or emergency savings without a plan
Debt reduction should not leave the borrower unable to handle essential expenses.
A Practical Decision Framework
Use this simple framework if your DTI is increasing.
Situation 1: Income is stable and debt is manageable
Continue repayment and avoid unnecessary new borrowing.
Situation 2: Income is stable but EMI burden is uncomfortable
Review expenses, refinance where genuinely beneficial and ask the lender about available restructuring options.
Situation 3: Income has fallen temporarily
Focus on short-term cash-flow management and communicate with lenders early.
Situation 4: Income has fallen permanently and full repayment is unrealistic
Explore formal restructuring and, where appropriate, Loan Settlement.
Situation 5: Multiple debts have already become overdue
Prepare a complete liability statement and seek professional financial/legal guidance rather than handling each debt separately without an overall plan.
Legal Considerations
A borrower remains responsible for contractual loan obligations unless a formal arrangement changes or resolves them.
If the account has entered recovery or legal proceedings, do not assume that beginning settlement discussions automatically stops the process.
Borrowers should carefully review:
- Legal notices
- Arbitration communications
- Court documents
- Lok Adalat notices
- Security-related notices
- Recovery correspondence
Where a judicial proceeding is already pending, settlement may require additional procedural steps depending on the circumstances.
RBI’s compromise-settlement framework specifically addresses situations where recovery proceedings are pending before a judicial forum. (rbi.org.in)
For complicated cases, independent legal advice may be appropriate.
Frequently Asked Questions
1. Does a high debt-to-income ratio make me eligible for loan settlement?
No. A high DTI is a sign of repayment pressure, but it does not automatically make a borrower eligible for settlement. The lender decides whether settlement can be considered.
2. What DTI ratio is considered too high in India?
There is no single universal DTI threshold applicable to every borrower and every lender. Different lenders use different credit assessment methods. For personal financial planning, a steadily rising ratio should be treated as a warning sign.
3. Can I settle a loan if my income has decreased?
You can discuss settlement with the lender if the income reduction has created genuine long-term repayment difficulty. Approval depends on the lender and the circumstances of the account.
4. Should I settle my loan as soon as my DTI increases?
No. A rising DTI should trigger a financial review, not an automatic settlement decision. Repayment, restructuring and other options should be compared first.
5. Can restructuring reduce my monthly EMI?
Depending on the lender’s policy and applicable framework, restructuring may modify repayment terms and can potentially change the repayment burden. It does not necessarily reduce the total cost of borrowing.
6. Can I take another loan to reduce my debt-to-income ratio?
A new loan can sometimes replace existing debt under better terms, but adding another EMI can also increase your debt burden. Calculate the total repayment obligation before borrowing.
7. Will loan settlement affect my CIBIL score?
Settlement can affect your credit history and future credit assessment. The account’s reporting should be understood before agreeing to the settlement.
8. Does RBI specify a fixed loan settlement percentage?
No. RBI’s compromise-settlement framework requires regulated entities to have appropriate policies but does not establish one fixed percentage for every borrower.
9. Can I settle multiple loans together?
You may seek professional assistance in assessing multiple debts, but each lender and account can have its own policy, documentation and settlement process. Do not assume that settling one account automatically resolves another.
10. What should I do if my DTI rises because of credit card debt?
Stop increasing the outstanding balance where possible, list all liabilities, calculate the actual repayment burden and assess whether you can repay the balances. If the debt has become structurally unaffordable, consider discussing appropriate resolution options.
11. Can a settled loan be removed from my credit report?
Settlement information is part of the credit history supplied by the lender and should not be assumed to disappear simply because the borrower has paid the settlement amount. Check the report for accuracy after the lender updates it.
12. Is debt settlement the same as loan restructuring?
No. Restructuring generally changes repayment terms so that the borrower can continue servicing the debt. Settlement involves a negotiated arrangement to resolve the lender’s claim.
Final Takeaway
A debt-to-income ratio that keeps rising is a financial warning signal. It tells you that debt is consuming an increasing share of your income or that your income is no longer keeping pace with your obligations.
The correct response is not automatically to Settle Loan.
Start by calculating every EMI and debt payment. Identify whether the problem comes from excessive borrowing, falling income, rising household expenses or a combination of these factors. Then determine whether normal repayment remains realistic.
If repayment is possible, focus on reducing the debt burden without taking unnecessary new credit. If the borrower can repay but needs modified terms, restructuring may be worth discussing with the lender.
Where genuine financial hardship makes full repayment unrealistic, loan settlement may be considered as a negotiated resolution, subject to lender approval and applicable policies.
Most importantly, do not wait for a rising DTI to turn into multiple defaults. Early assessment gives borrowers more time to understand their options, protect essential finances and make a properly informed debt-resolution decision.