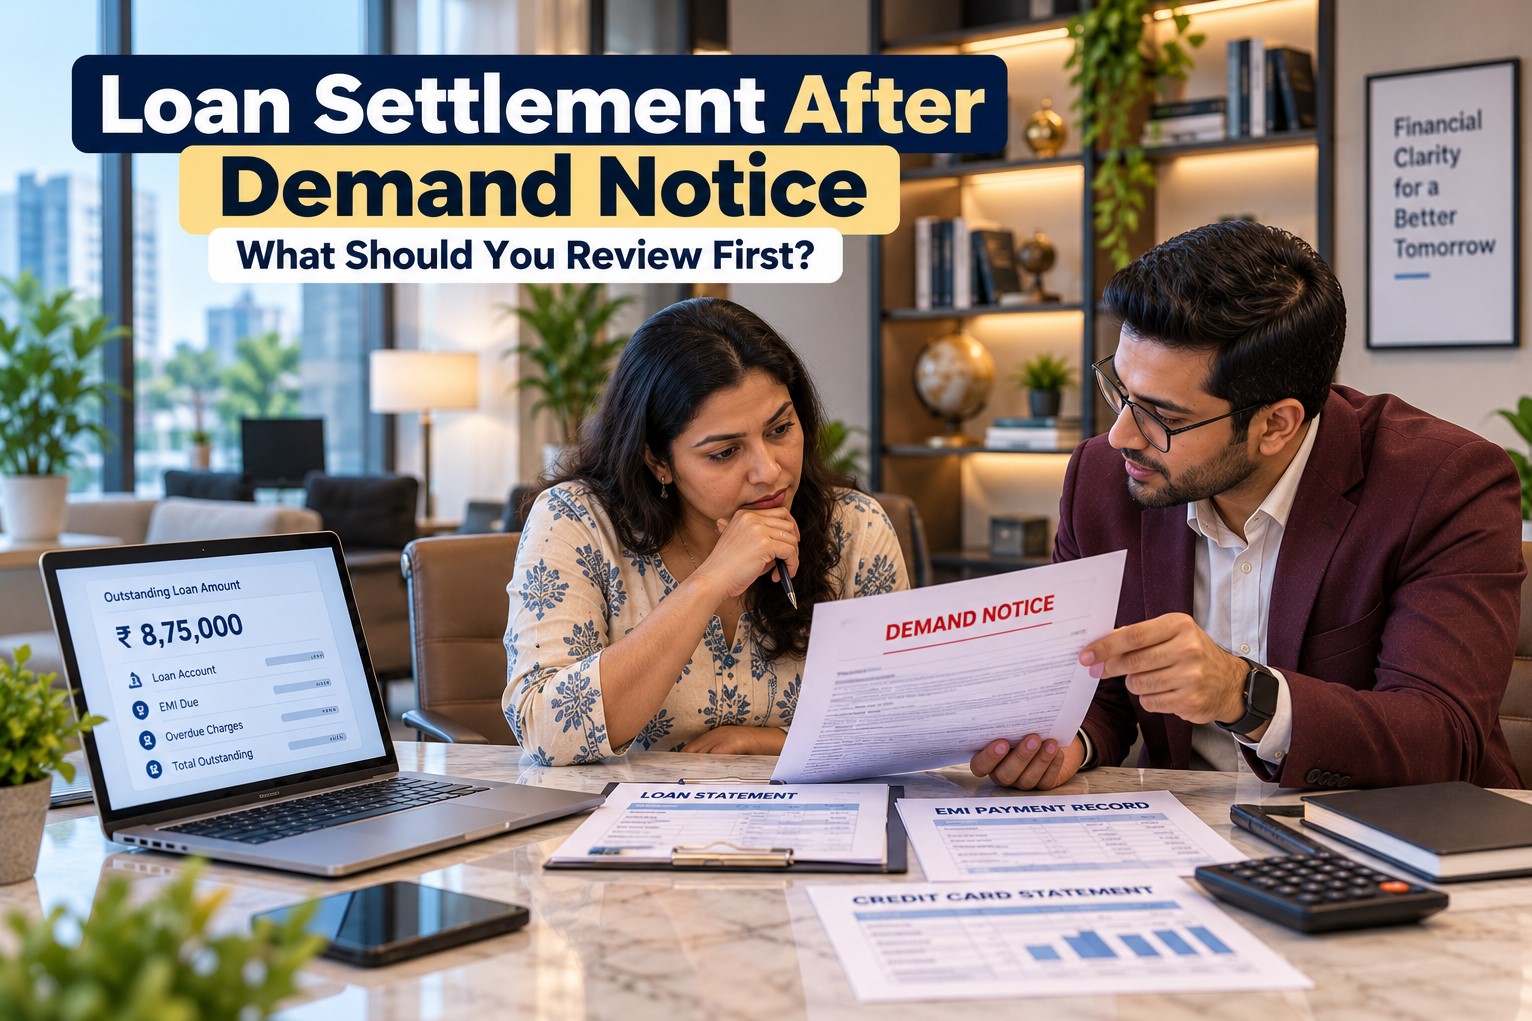
Receiving a demand notice for an unpaid loan can be stressful, but the first response should not be an immediate payment or settlement promise. A borrower should first verify the notice, lender details, loan account number, outstanding amount, overdue period, documents referred to in the notice and the deadline for responding.
A demand notice does not automatically mean that loan settlement is the only option. Depending on the account and the borrower’s financial position, the borrower may still be able to discuss repayment, restructuring or a negotiated settlement with the lender. If legal proceedings have already started, the borrower should also understand what stage the matter has reached before making any commitment.
Loan settlement after a demand notice can be considered where the lender’s policy permits it and the borrower has genuine difficulty repaying the full liability. RBI’s framework recognises compromise settlements as negotiated arrangements between regulated entities and borrowers, subject to the applicable policy and regulatory requirements.
The important rule is simple: review first, negotiate second, pay only after verifying the terms.
What Is a Loan Demand Notice?
A demand notice is a formal communication from a lender, financial institution, authorised recovery entity or other party handling the debt. It generally informs the borrower that an amount is claimed as outstanding and asks for payment or another specified action.
The exact meaning depends on the document.
Not every document labelled “notice” has the same legal effect.
It may be:
- A payment reminder
- An overdue notice
- A demand for repayment
- A pre-legal recovery communication
- A notice connected with arbitration
- A notice from a legal representative
- A notice relating to secured assets
- A communication connected with an existing court or recovery proceeding
Therefore, borrowers should read the entire document instead of focusing only on the amount demanded.
The First 6 Things to Check
Before discussing Settle Loan options, check these six areas.
1. Who issued the notice?
Confirm the name of the bank, NBFC, financial institution, authorised recovery agency or legal representative.
If the communication has come from someone claiming to represent the lender, verify that relationship through the lender’s official channels.
2. Which loan account does it relate to?
Check:
- Loan account number
- Borrower’s name
- Co-borrower details
- Loan type
- Original loan amount
- Date of loan
- Branch or servicing entity
An incorrect account reference should be raised immediately.
3. What amount is being demanded?
Do not assume the demand figure is the same as the original outstanding balance.
Check the breakup of:
- Principal
- Interest
- Overdue instalments
- Applicable penal charges
- Other contractual charges
- Legal or recovery-related amounts, where applicable
- Payments already made
4. What period does the notice cover?
Check when the account allegedly became overdue and whether the notice correctly reflects your payment history.
Keep bank statements and payment receipts ready.
5. What deadline is mentioned?
A notice may contain a specific response or payment deadline.
Do not ignore it.
6. What action does the notice say may follow?
Read the document carefully for references to recovery proceedings, arbitration, court proceedings, secured assets or other legal steps.
If the document has legal consequences, professional legal advice may be appropriate.
Do Not Treat Every Demand Notice as a Settlement Offer
This is an important distinction.
A demand notice may simply ask the borrower to clear outstanding dues.
It does not necessarily mean that the lender has offered a settlement.
A settlement is a separate negotiated arrangement in which the lender agrees to resolve its claim under specified terms.
RBI’s compromise-settlement framework defines compromise settlement as a negotiated arrangement to fully settle the claims of the regulated entity in cash, potentially involving a sacrifice of part of the amount due. Regulated entities must have Board-approved policies governing such settlements.
Therefore:
Demand notice: “Pay the amount claimed or take the specified action.”
Settlement proposal: “The lender agrees to resolve the claim under specific negotiated terms.”
These are not the same document.
Why You Should Verify the Outstanding Amount First
A borrower should never negotiate settlement using an old loan statement.
Ask for the latest account statement or obtain the relevant account details through the lender’s official channel.
For example, suppose a borrower originally borrowed ₹8 lakh.
After several years, the borrower believes only ₹4 lakh remains.
The demand notice shows ₹5.6 lakh.
Instead of immediately assuming the lender has made an error, the borrower should request the account calculation.
The difference could involve:
- Unpaid instalments
- Accrued interest
- Applicable charges
- Previous payment adjustments
- Other contractual amounts
If there is a genuine discrepancy, raise it with the lender and preserve the communication.
What If You Have Already Paid Some Amount?
Collect proof before responding.
Useful evidence includes:
- Bank statements
- UPI or electronic payment records
- Loan receipts
- NACH or ECS records
- Salary-account payment history
- Email confirmations
- Previous settlement discussions
- Statements received from the lender
Create a simple payment timeline.
For example:
| Date | Amount Paid | Payment Method | Reference |
|---|---|---|---|
| 10 Jan | ₹20,000 | Bank transfer | Transaction ID |
| 10 Feb | ₹20,000 | NACH | EMI debit |
| 15 Mar | ₹10,000 | UPI | Transaction ID |
This can help identify whether the lender’s statement and your records match.
Check Whether the Notice Is Genuine
Loan recovery scams can involve fake payment requests and impersonation.
Before paying anyone, verify:
- Lender name
- Official communication channel
- Loan account number
- Authorised payment account
- Contact details
- Notice reference number
- Name and designation of the sender
- Whether the sender is actually authorised by the lender
Do not transfer money to a personal bank account merely because someone claims to be a recovery agent.
If you are unsure, contact the lender through its official customer-care or grievance channel and verify the notice.
What If the Notice Comes From a Lawyer?
A notice issued by a lawyer should not be ignored.
Read:
- The name of the lender
- The amount claimed
- The legal basis mentioned
- Relevant dates
- Documents referred to
- Response deadline
- Action threatened if payment is not made
If the allegations or amount appear incorrect, collect your records before responding.
If the notice relates to court proceedings, arbitration or another formal legal process, consult a qualified lawyer who can examine the actual document.
A loan-settlement service can help with financial resolution discussions, but it should not replace independent legal advice where formal legal proceedings require it.
Can You Settle a Loan After Receiving a Demand Notice?
Potentially, yes.
But a demand notice does not create an automatic right to settlement.
The lender decides whether a settlement proposal can be considered under its applicable policy.
RBI’s 2023 framework provides for compromise settlements by regulated entities and requires Board-approved policies covering the process, including conditions and approval authority.
This means a borrower may approach the lender and ask whether a formal settlement route is available.
The borrower should be prepared to explain:
- Current income
- Financial hardship
- Existing liabilities
- Household obligations
- Available funds
- Why full repayment is difficult
- Proposed payment capacity
When Is Settlement More Relevant?
Settlement may be more relevant where there is genuine, continuing financial difficulty.
Examples include:
- Long-term job loss
- Permanent income reduction
- Business closure
- Major unavoidable expenses
- Multiple overdue loans
- Severe debt burden
- Inability to maintain the existing EMI
- Lack of realistic ability to repay the full liability
However, settlement should not be assumed to be appropriate simply because a notice has been received.
If the borrower can repay the debt under normal terms, continuing repayment may be more appropriate.
If the borrower can repay with modified terms, restructuring may need to be explored.
Settlement vs Restructuring After a Demand Notice
These options have different purposes.
| Option | Main purpose | Basic idea |
|---|---|---|
| Normal repayment | Complete contractual repayment | Continue paying as agreed |
| Restructuring | Address financial difficulty | Modify repayment terms where available |
| Settlement | Resolve the lender’s claim through negotiation | Pay the agreed settlement amount under documented terms |
RBI’s stressed-assets framework describes restructuring as concessions granted by a lender for economic or legal reasons relating to financial difficulty, which can include modifications to payment period, instalments or other terms.
Therefore, a borrower should not jump directly from a demand notice to settlement without considering whether another formal resolution is realistic.
What Should You Tell the Lender?
Keep the communication factual.
Explain:
- You have received the notice.
- You are reviewing the account.
- You want confirmation of the current outstanding amount.
- You want to understand the available repayment or resolution options.
- If full repayment is not possible, you want to know whether a formal settlement process is available.
Do not promise an amount you cannot arrange.
For example, if you can realistically arrange ₹2 lakh but tell the lender you will arrange ₹5 lakh because you are under pressure, you may create another financial problem.
A settlement proposal should be based on actual affordability.
What Documents Should You Prepare?
A strong settlement discussion is easier when the borrower has complete records.
Keep:
- Demand notice
- Latest loan statement
- Original loan agreement
- EMI schedule
- Bank statements
- Salary slips
- Income proof
- Employment-related documents
- Business financial records, where relevant
- Other loan statements
- Credit card statements
- Credit report
- Medical or emergency expense records, if relevant
- Previous lender correspondence
- Legal notices
- Payment receipts
The exact documents depend on the account and lender.
What Should a Settlement Letter Contain?
If the lender agrees to a settlement, do not rely on a verbal statement.
Review the written settlement document carefully.
It should clearly identify, as applicable:
- Borrower name
- Loan account number
- Total outstanding amount
- Settlement amount
- Payment deadline
- Instalment schedule, if permitted
- Conditions of settlement
- Consequences of non-payment
- Treatment of remaining dues
- Account resolution status
- Legal proceedings, if applicable
- Security or collateral implications
- Co-borrower or guarantor implications
The borrower should keep the signed or officially issued document.
What Happens If Legal Proceedings Have Already Started?
This requires greater caution.
A borrower should determine whether the notice is:
- Before legal proceedings
- Part of an arbitration process
- Connected to a court case
- Related to recovery proceedings
- Related to enforcement of security
Settlement discussions do not automatically erase a pending legal proceeding.
RBI’s compromise-settlement framework specifically states that where recovery proceedings have been commenced under a judicial forum and remain pending, a settlement is subject to obtaining a consent decree from the concerned judicial authority.
Therefore, if a case is already pending, the borrower should not assume that paying a negotiated amount privately will automatically close the legal matter.
The settlement documentation and legal status should be checked carefully.
What If the Loan Is Secured?
A demand notice connected with a secured loan requires additional attention.
For example:
- Home loan
- Loan against property
- Certain vehicle finance arrangements
- Other secured borrowing
The borrower should identify:
- The asset offered as security
- Current outstanding amount
- Notice type
- Legal stage
- Security enforcement provisions
- Whether any possession or sale process has been initiated
Do not treat a secured-loan demand notice in the same way as an ordinary unsecured personal-loan reminder.
If property or another significant asset is involved, legal advice can be particularly important.
What About Recovery Agents?
After an account becomes overdue, borrowers may receive calls or other communications regarding repayment.
Borrowers should maintain records of communications and verify that the person contacting them is authorised.
Do not:
- Share OTPs
- Share passwords
- Give banking credentials
- Transfer money to unverified accounts
- Sign blank documents
- Hand over original property documents without proper verification
If there is inappropriate recovery conduct, borrowers can separately review Recovery Agent Harassment and the lender’s grievance mechanism.
How Does Settlement Affect Your Credit Report?
A settlement can affect the borrower’s credit history.
Credit Information Companies receive credit information from reporting members, so the account’s status and repayment history can influence future credit assessment.
This matters if you plan to apply for:
- Personal loan
- Home loan
- Vehicle loan
- Credit card
- Business finance
A borrower should therefore understand the credit consequences before accepting settlement.
After resolving the debt, maintaining timely repayments on other active accounts and using credit responsibly can help rebuild financial stability. A Credit Score Builder strategy may be useful during that stage.
Does RBI Fix a Loan Settlement Percentage?
No.
RBI’s compromise-settlement framework does not establish one universal settlement percentage for all borrowers.
Regulated entities are required to have Board-approved policies covering compromise settlements, including the process and permissible sacrifice for different categories of exposures.
Therefore, statements such as:
- “RBI allows every borrower to settle at 50%.”
- “The bank must waive all interest.”
- “Every demand notice can be closed for a fixed percentage.”
should not be treated as universal rules.
The actual terms depend on the lender, account, circumstances and applicable policy.
What If You Cannot Pay the Amount in the Demand Notice?
Do not ignore the notice simply because you cannot arrange the full amount.
Instead:
First, verify the account
Confirm the amount and account details.
Second, assess affordability
Calculate how much you can genuinely arrange without creating another unaffordable liability.
Third, communicate with the lender
Ask about available repayment, restructuring or settlement options.
Fourth, obtain everything in writing
Do not make large payments based only on telephone conversations.
Fifth, address legal deadlines
If the notice has a formal legal response deadline, take appropriate legal advice where required.
This approach is safer than simply stopping communication.
Practical Example: Personal Loan Demand Notice
Consider Amit, who took a ₹7 lakh personal loan.
After a job loss, he missed several EMIs. He later received a demand notice claiming ₹6.1 lakh.
Amit believes the amount is too high because he had already paid approximately ₹2 lakh toward the loan.
Instead of immediately offering ₹3 lakh as a settlement, he should first:
- Obtain the latest loan statement.
- Match it against his bank records.
- Check principal, interest and applicable charges.
- Verify the notice and sender.
- Determine whether any legal proceeding is pending.
- Assess his current income and available funds.
- Ask the lender about available resolution options.
- If full repayment is unrealistic, ask whether a formal settlement can be considered.
- Review any settlement letter before paying.
- Retain all payment and closure documentation.
This process gives him a clearer understanding of what he is actually being asked to resolve.
Common Mistakes After Receiving a Demand Notice
Ignoring the notice
Silence does not resolve the debt and may allow the matter to progress.
Paying the recovery agent personally
Payments should be made only through verified and authorised channels.
Negotiating without the latest statement
You cannot properly evaluate a settlement without knowing the actual account position.
Assuming the notice itself is a settlement offer
A demand for payment and a settlement proposal are different things.
Making a settlement promise you cannot fulfil
Only propose an amount you can realistically arrange.
Taking another expensive loan immediately
New borrowing can increase the overall debt burden.
Ignoring legal language
If the document refers to arbitration, court proceedings or enforcement of security, understand what it means before responding.
Believing settlement automatically improves CIBIL
Settlement may have adverse implications for credit reporting. It is a debt-resolution decision, not a credit-repair shortcut.
A 24-Hour Review Checklist
If you have just received a demand notice, start with these checks:
Document: Is the notice genuine and from the correct lender or authorised representative?
Account: Does the loan account number match your records?
Amount: Does the demanded amount match the latest statement?
Payments: Have all your previous payments been credited?
Dates: Are the overdue dates and repayment history correct?
Deadline: Is there a specific response or payment date?
Legal status: Does the notice mention court, arbitration, security enforcement or another formal proceeding?
Affordability: Can you realistically pay the claimed amount?
Resolution: Should you ask about repayment, restructuring or settlement?
Documentation: Will you have written confirmation before making any settlement payment?
This checklist helps separate the immediate facts from the stress caused by receiving the notice.
Frequently Asked Questions
1. Can I settle my loan after receiving a demand notice?
You can ask the lender whether a formal settlement is available, but receiving a demand notice does not guarantee settlement. The lender decides according to its applicable policy.
2. Does a demand notice mean the loan is already in court?
Not necessarily. A demand notice can be a recovery communication without being a court order. Read the document carefully to determine whether it refers to any judicial, arbitration or other legal proceeding.
3. Should I pay the full amount mentioned in the notice immediately?
First verify the notice, account details and amount. If you believe the figure is incorrect or you cannot afford it, communicate with the lender and obtain appropriate advice rather than making a rushed payment.
4. Can I negotiate the settlement amount after receiving a demand notice?
You can request and negotiate a settlement, but the lender is not required to accept your proposed amount.
5. Does RBI guarantee loan settlement after a demand notice?
No. RBI provides a regulatory framework for compromise settlements by regulated entities but does not guarantee settlement for an individual borrower or prescribe one fixed settlement percentage.
6. Can I settle a loan if a legal case is already pending?
A settlement may still be possible in some circumstances, but the legal process must be considered. RBI’s framework states that where recovery proceedings are pending before a judicial forum, a settlement is subject to the concerned judicial authority’s consent decree.
7. Will settlement affect my CIBIL report?
It can. Settlement is different from normal full repayment and can affect how future lenders assess your credit history.
8. What if the demand notice contains an incorrect outstanding amount?
Collect your payment records and request a detailed account statement from the lender. Raise the discrepancy through the lender’s appropriate grievance channel.
9. Can I ask for restructuring instead of settlement?
You can ask the lender whether restructuring or another repayment arrangement is available. Restructuring and settlement are different resolution methods.
10. Should I take another loan to pay the demand notice?
Do not assume that new borrowing is the solution. Compare the interest rate, new EMI, total repayment and your actual income before taking additional debt.
11. Can a personal loan be settled after receiving a demand notice?
A personal loan may be considered for settlement if the lender’s applicable policy permits it and the lender approves the proposal. The borrower’s financial circumstances and account status are relevant.
12. What documents should I keep after settlement?
Keep the settlement letter, payment receipts, bank transaction proof, final account statement and any documentation confirming the agreed resolution. If legal proceedings were involved, retain the relevant legal documents as well.
Conclusion
A demand notice should be treated as a serious financial communication, but it should not trigger a rushed settlement payment.
The first step is to verify who issued the notice, which loan account it concerns, how the outstanding amount was calculated, what payments have already been credited, what deadline applies and whether any legal proceeding is involved.
Once the position is clear, the borrower can assess the available options. These may include normal repayment, restructuring or Loan Settlement, depending on financial circumstances and lender policy.
If full repayment is genuinely unaffordable, a formal settlement discussion may provide one possible route. But the borrower should review the settlement terms, credit-reporting implications, legal status and payment conditions before agreeing.
Most importantly, never rely on an informal promise that “the loan will be closed” after making a payment. Obtain the lender’s terms in writing, use verified payment channels and retain the complete record.
For borrowers dealing with serious repayment difficulty, Debt Settlement guidance can help in understanding the financial-resolution process, while Personal Loan Settlement may be relevant where the demand notice concerns an unsecured personal loan.
A demand notice is a point where careful documentation and timely action matter more than a rushed decision.